
EPISODE · Jul 1, 2020 · 1 MIN
Garman-Klass Volatility Calculation – Volatility Analysis in Python
from Harbourfront Technologies · host Harbourfront Technologies
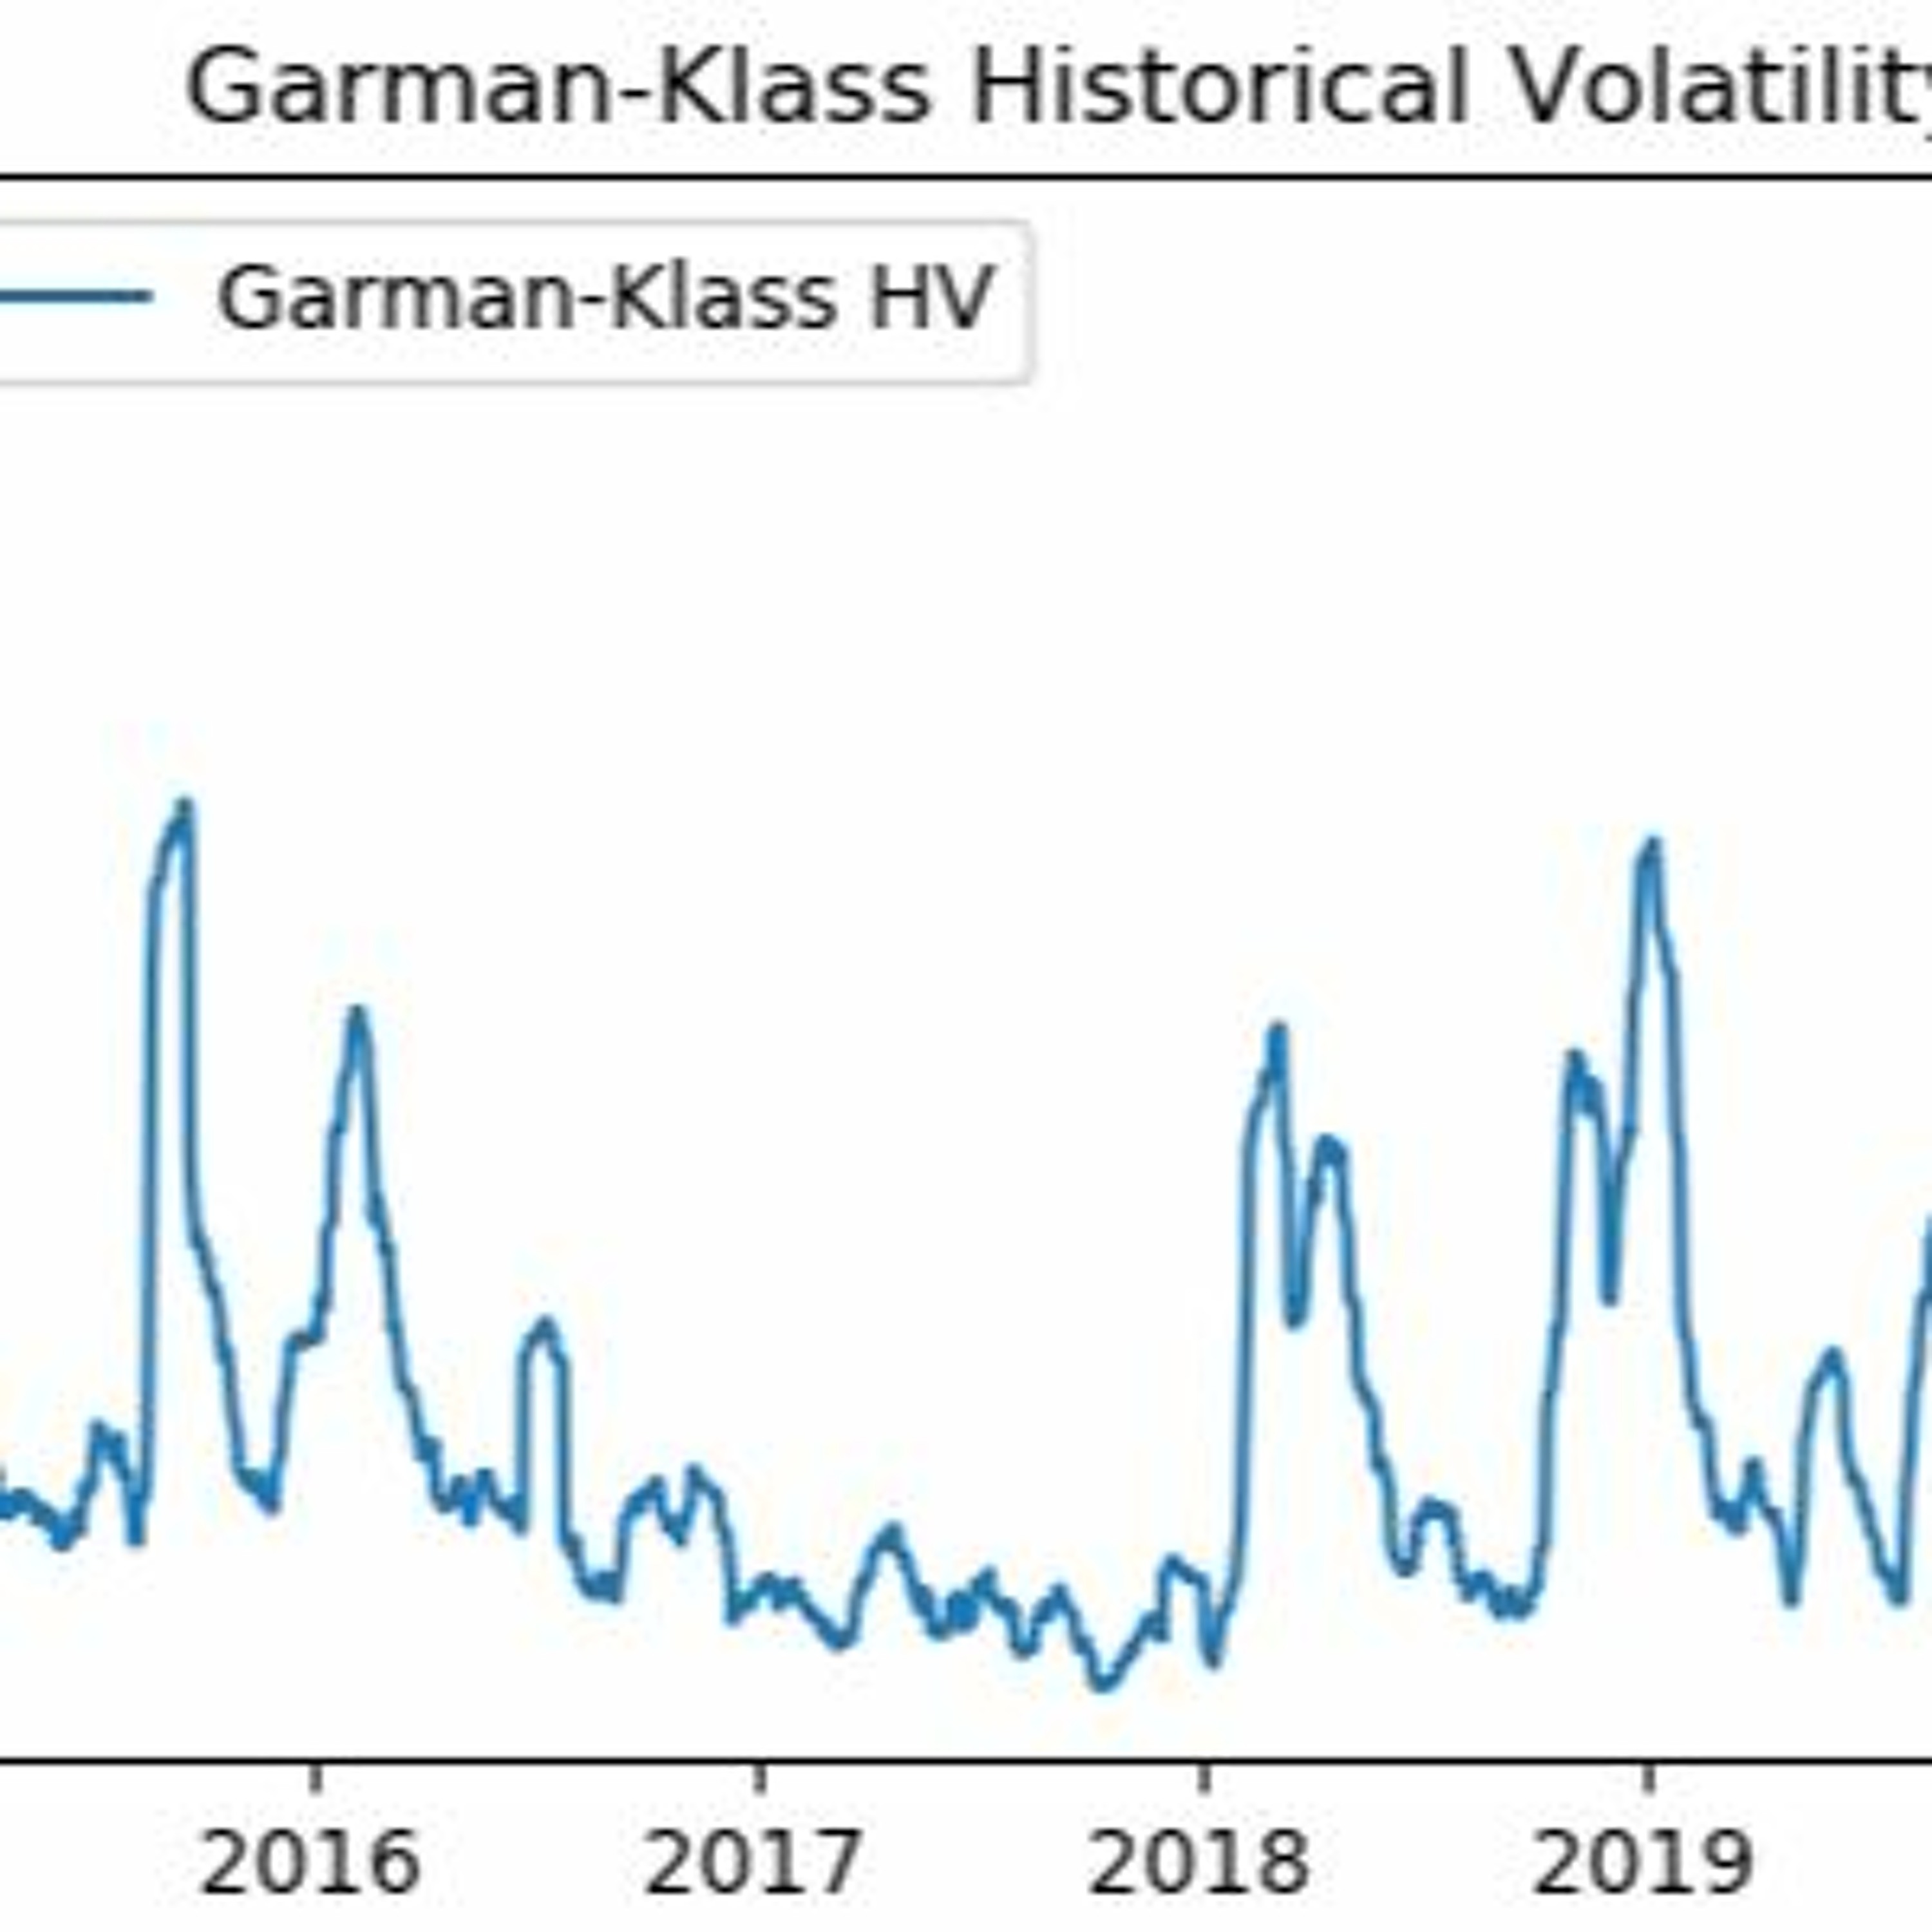
In the previous post, we introduced the Parkinson volatility estimator that takes into account the high and low prices of a stock. In this follow-up post, we present the Garman-Klass volatility estimator that uses not only the high and low but also the opening and closing prices. http://tech.harbourfronts.com/trading/garman-klass-volatility-calculation-volatility-analysis-python/
Embed this episode
Ready to play
Garman-Klass Volatility Calculation – Volatility Analysis in Python
No transcript for this episode yet
Similar Episodes
No similar episodes found.