
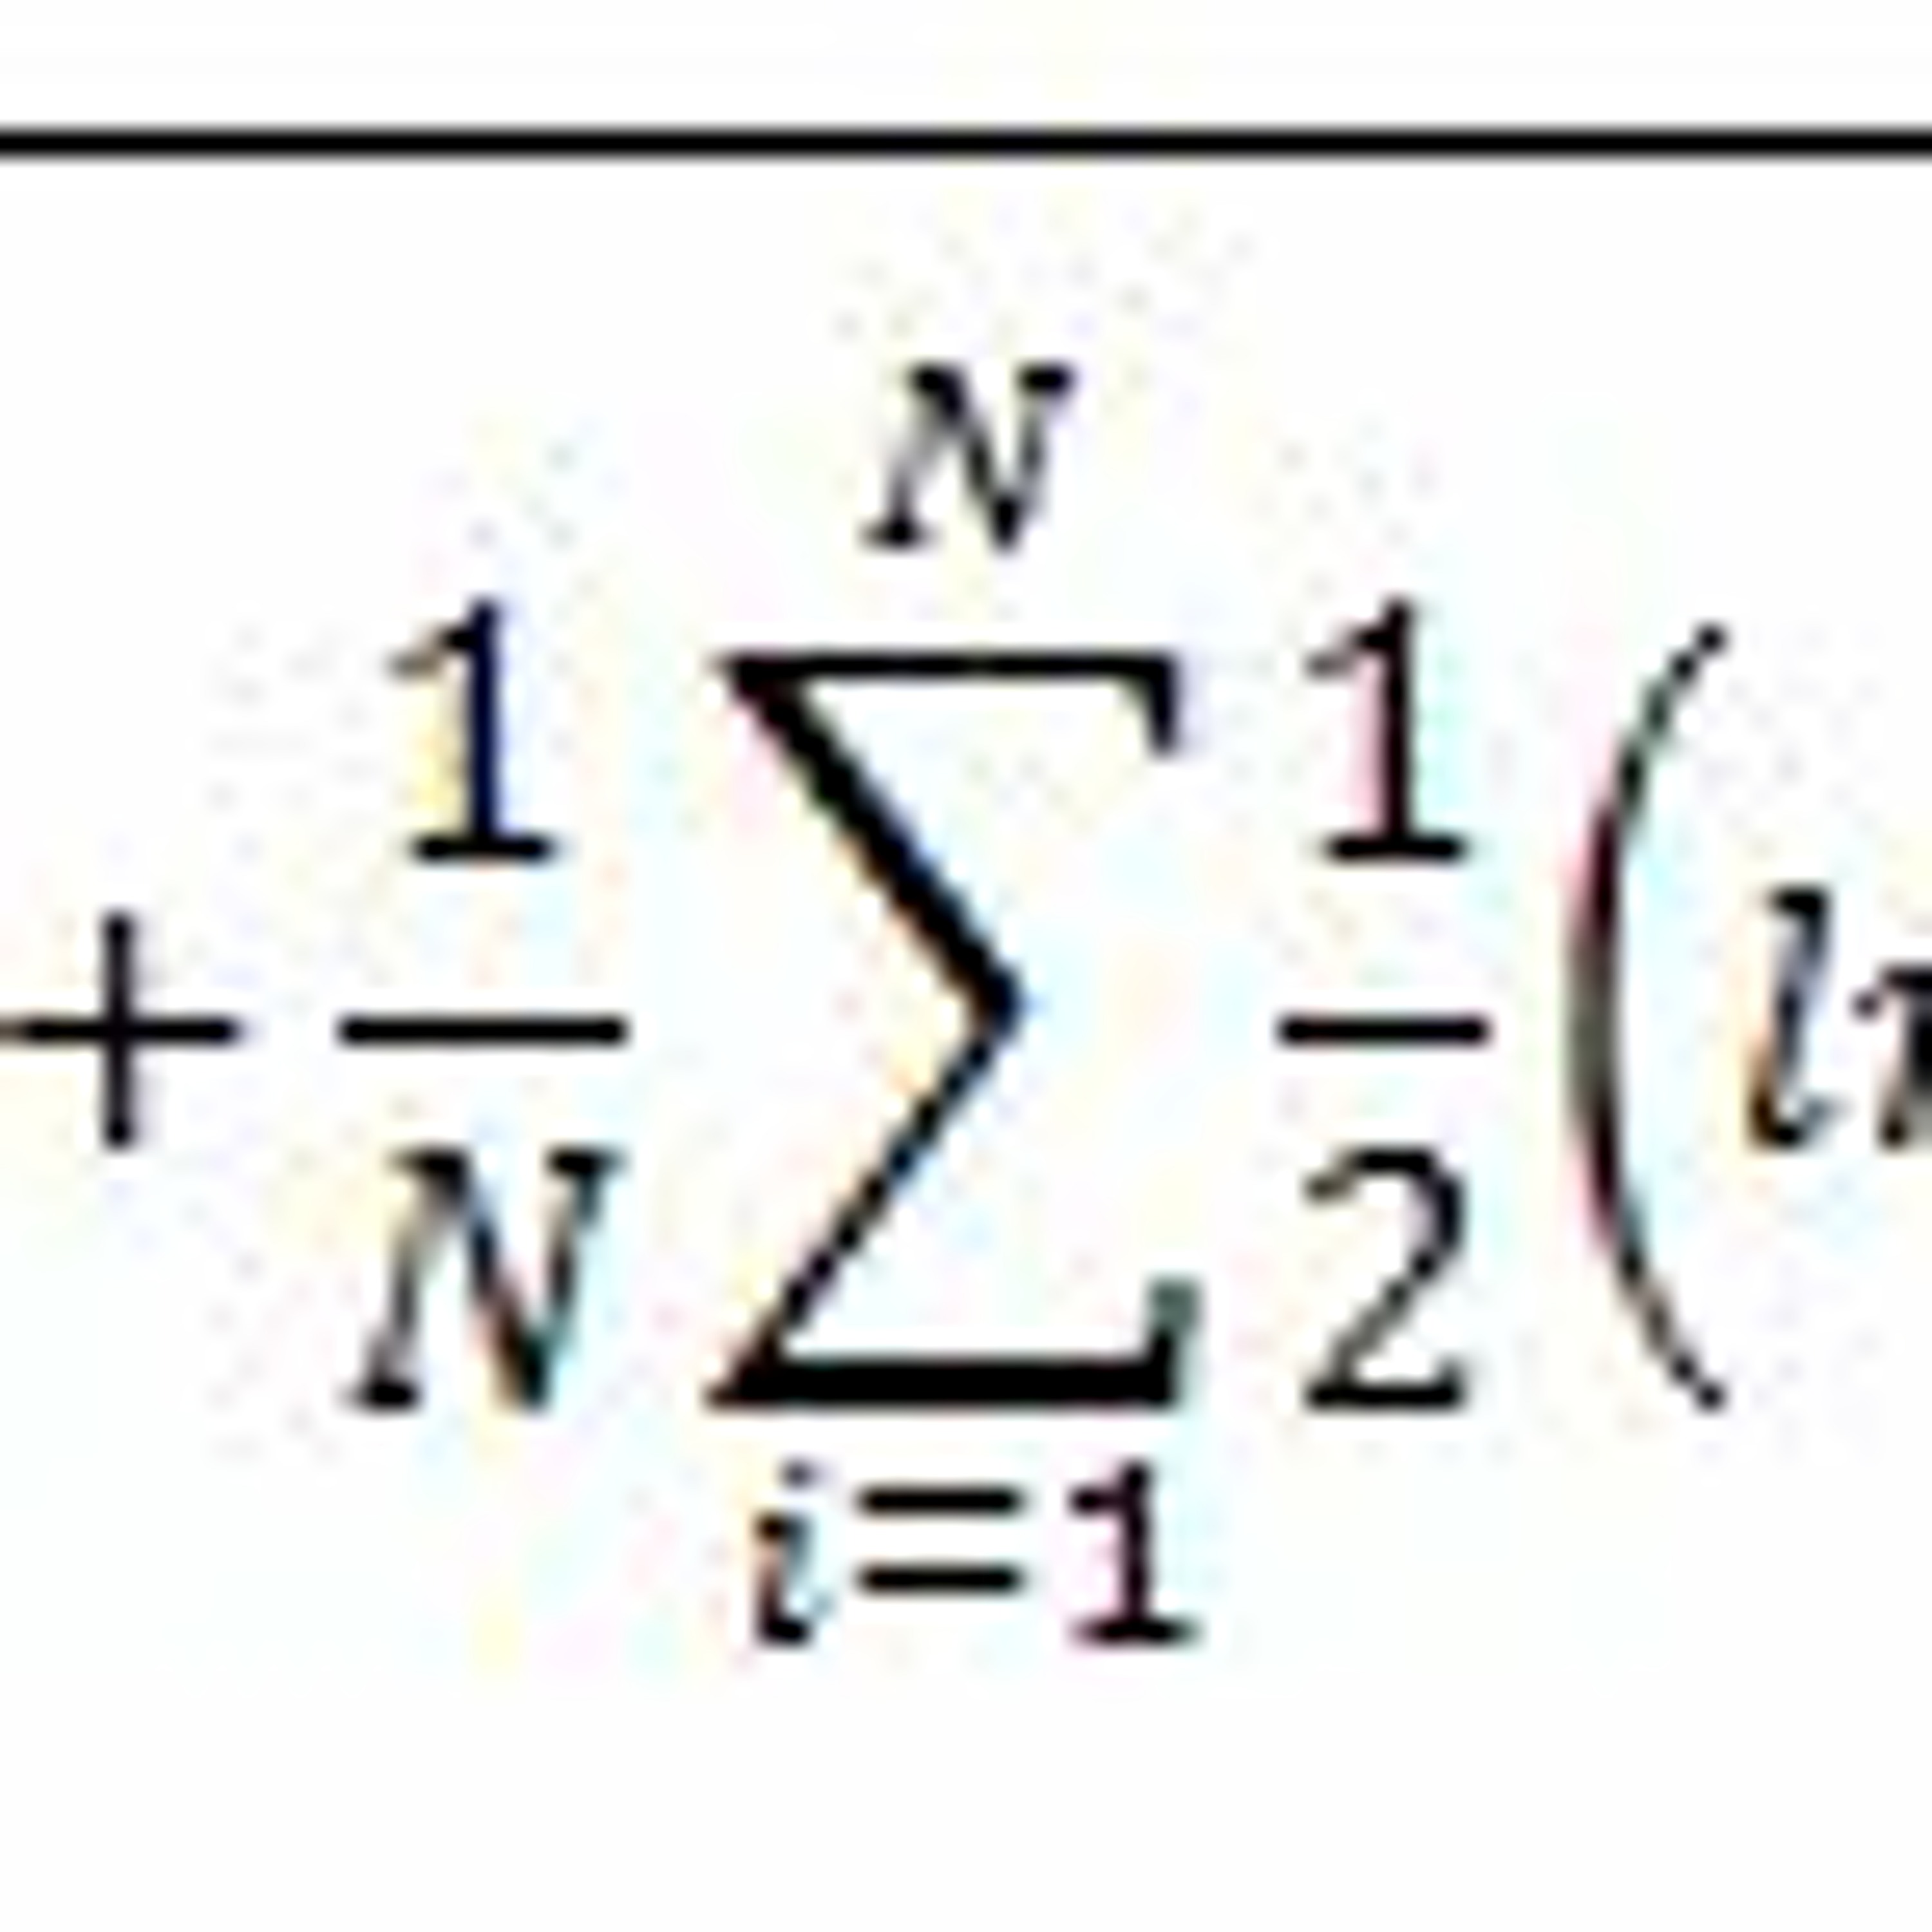
EPISODE · Jul 28, 2020 · 1 MIN
Garman-Klass-Yang-Zhang Historical Volatility Calculation – Volatility Analysis in Python
from Harbourfront Technologies · host Harbourfront Technologies
We present an extension of the Garman-Klass volatility estimator that also takes into consideration overnight jumps. Garman-Klass-Yang-Zhang (GKYZ) volatility estimator consists of using the returns of open, high, low, and closing prices in its calculation. It also uses the previous day’s closing price. http://tech.harbourfronts.com/trading/garman-klass-yang-zhang-historical-volatility-calculation-volatility-analysis-python/
Embed this episode
Ready to play
Garman-Klass-Yang-Zhang Historical Volatility Calculation – Volatility Analysis in Python
No transcript for this episode yet
Similar Episodes
No similar episodes found.