
EPISODE · Apr 26, 2021 · 1 MIN
Mean - Reverting Trading System - Quantitative Trading In Python
from Harbourfront Technologies · host Harbourfront Technologies
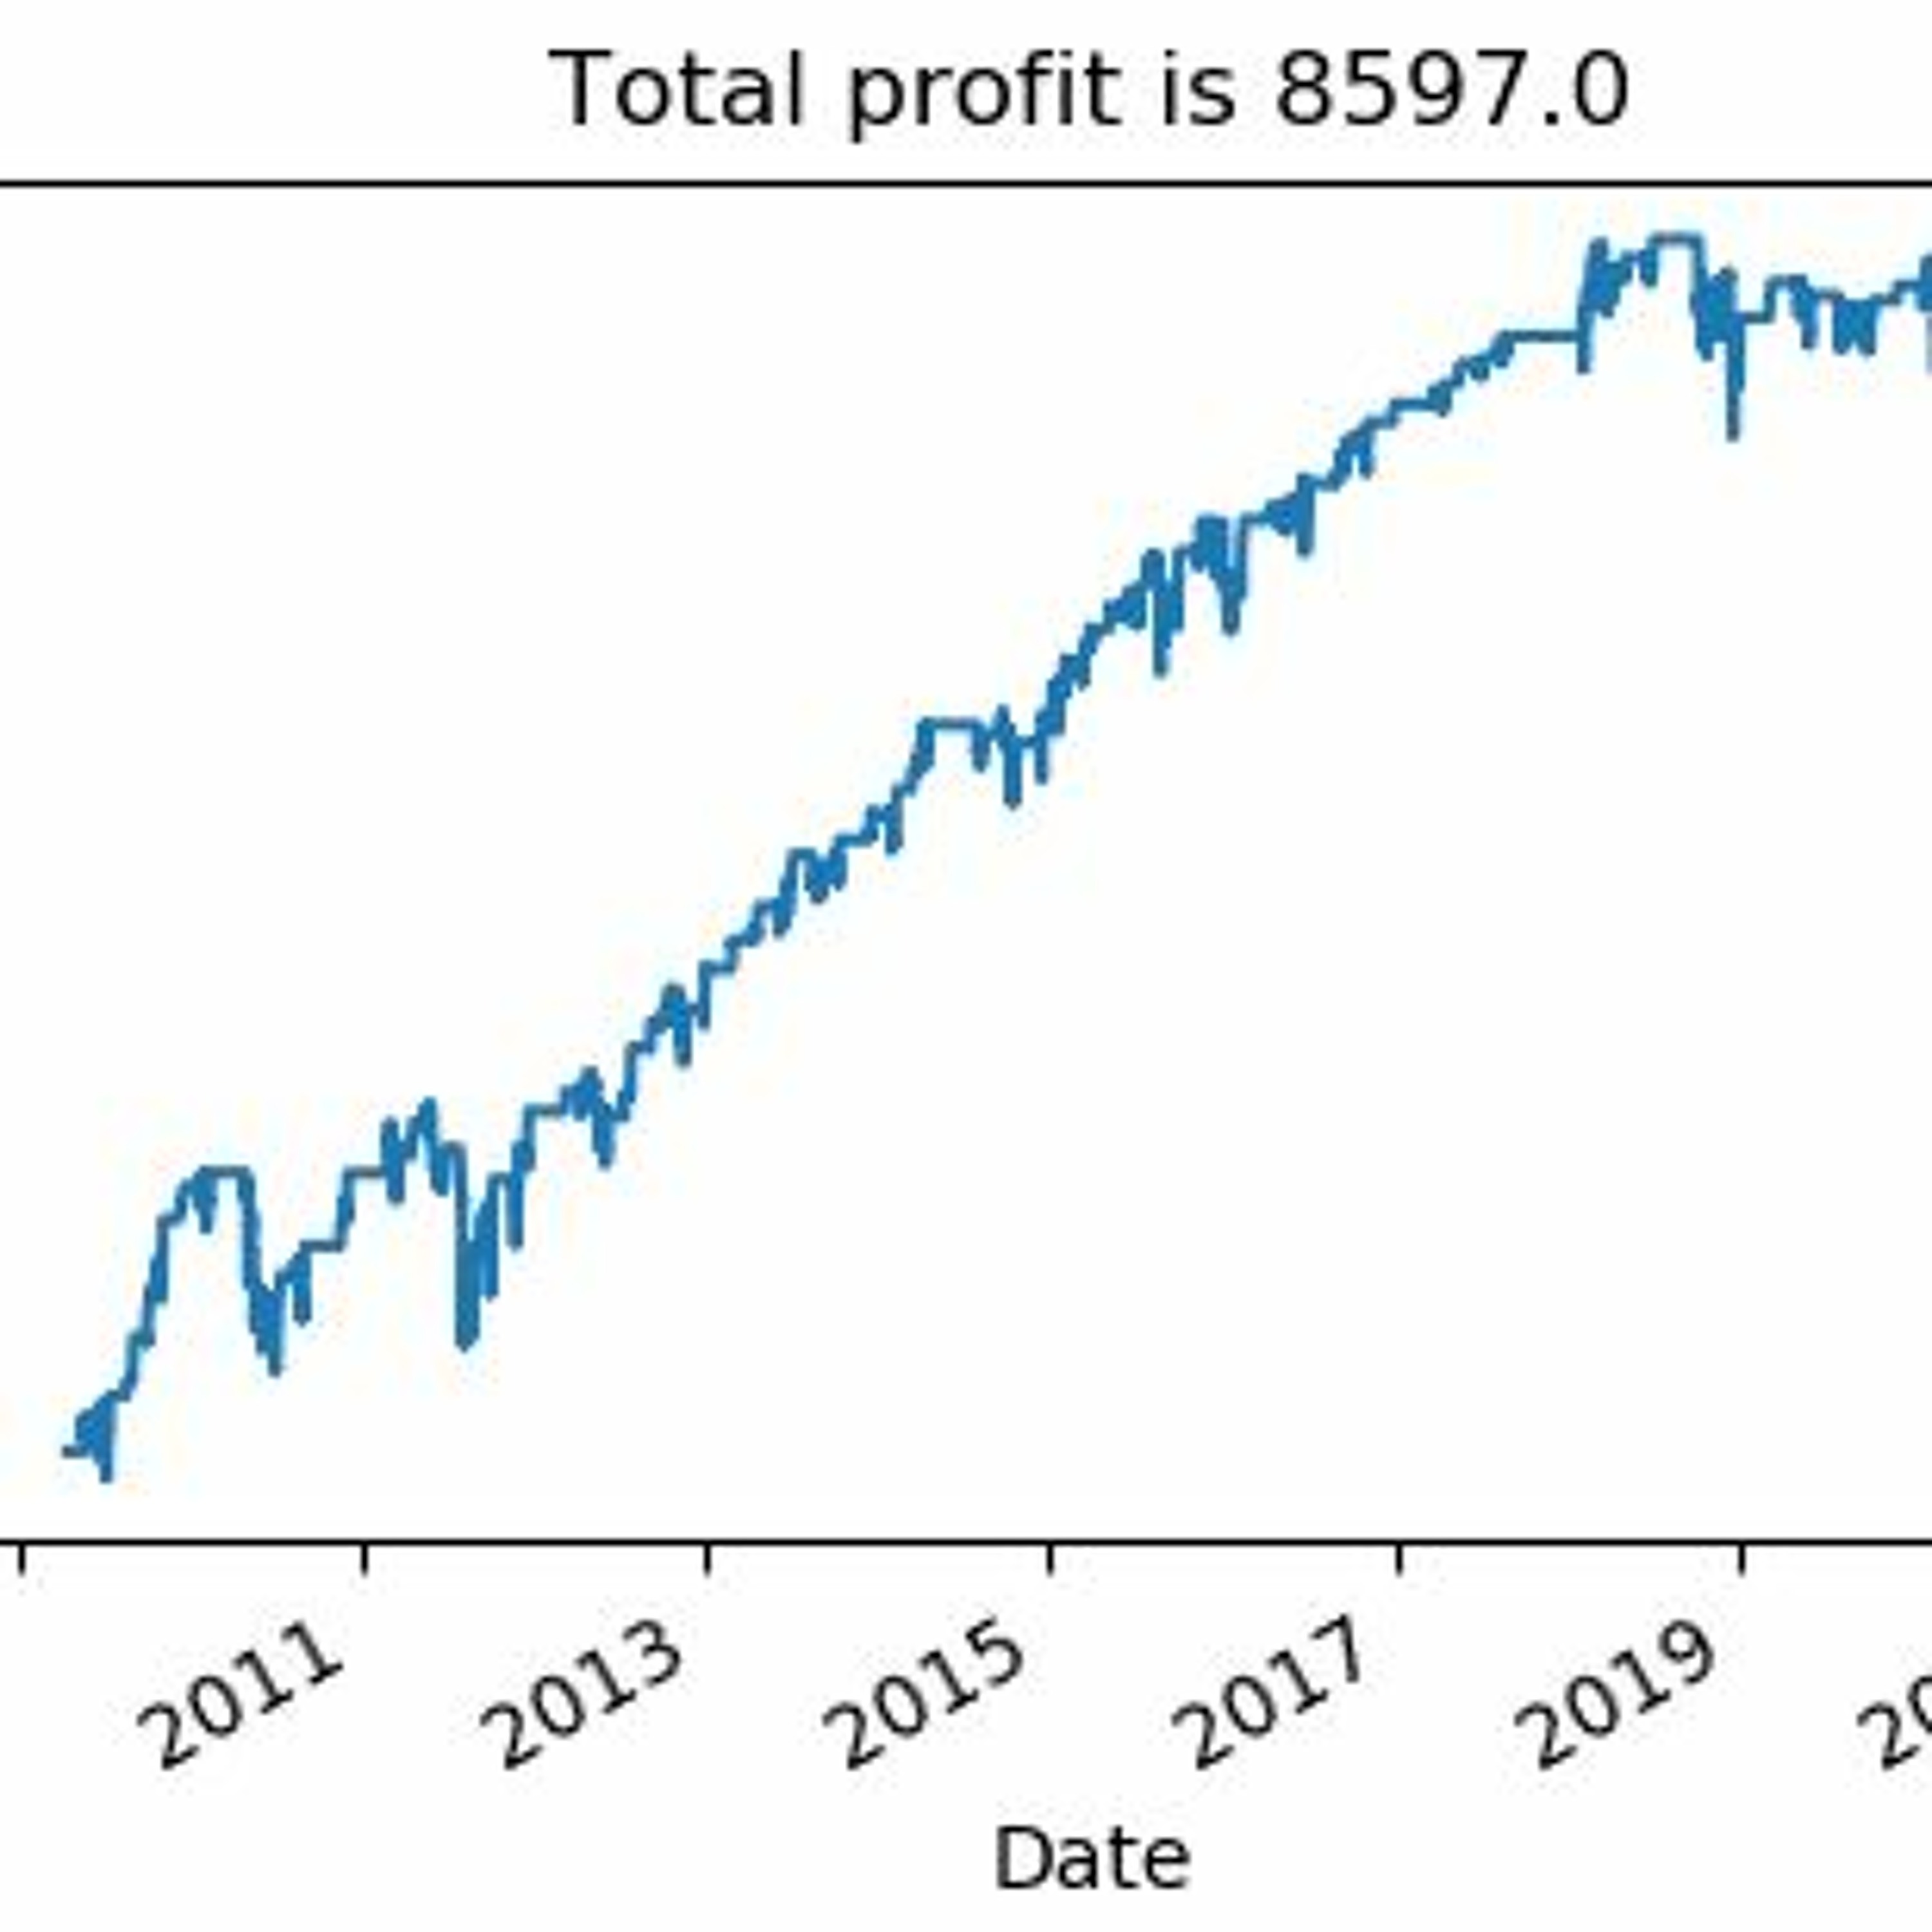
We develop a simple trading system exploiting the mean-reverting behaviour of the SP500 market index. To generate buy and sell signals, we will use simple moving averages as noise filters. Since we know that the SP500 is mean-reverting in a short term, we will use short-term moving averages. http://tech.harbourfronts.com/mean-reverting-trading-system-quantitative-trading-in-python/
Embed this episode
Ready to play
Mean - Reverting Trading System - Quantitative Trading In Python
No transcript for this episode yet
Similar Episodes
No similar episodes found.