One Winner, Six Shipwrecks
from SEA of Startups Hosted by Kevin Brockland CFA
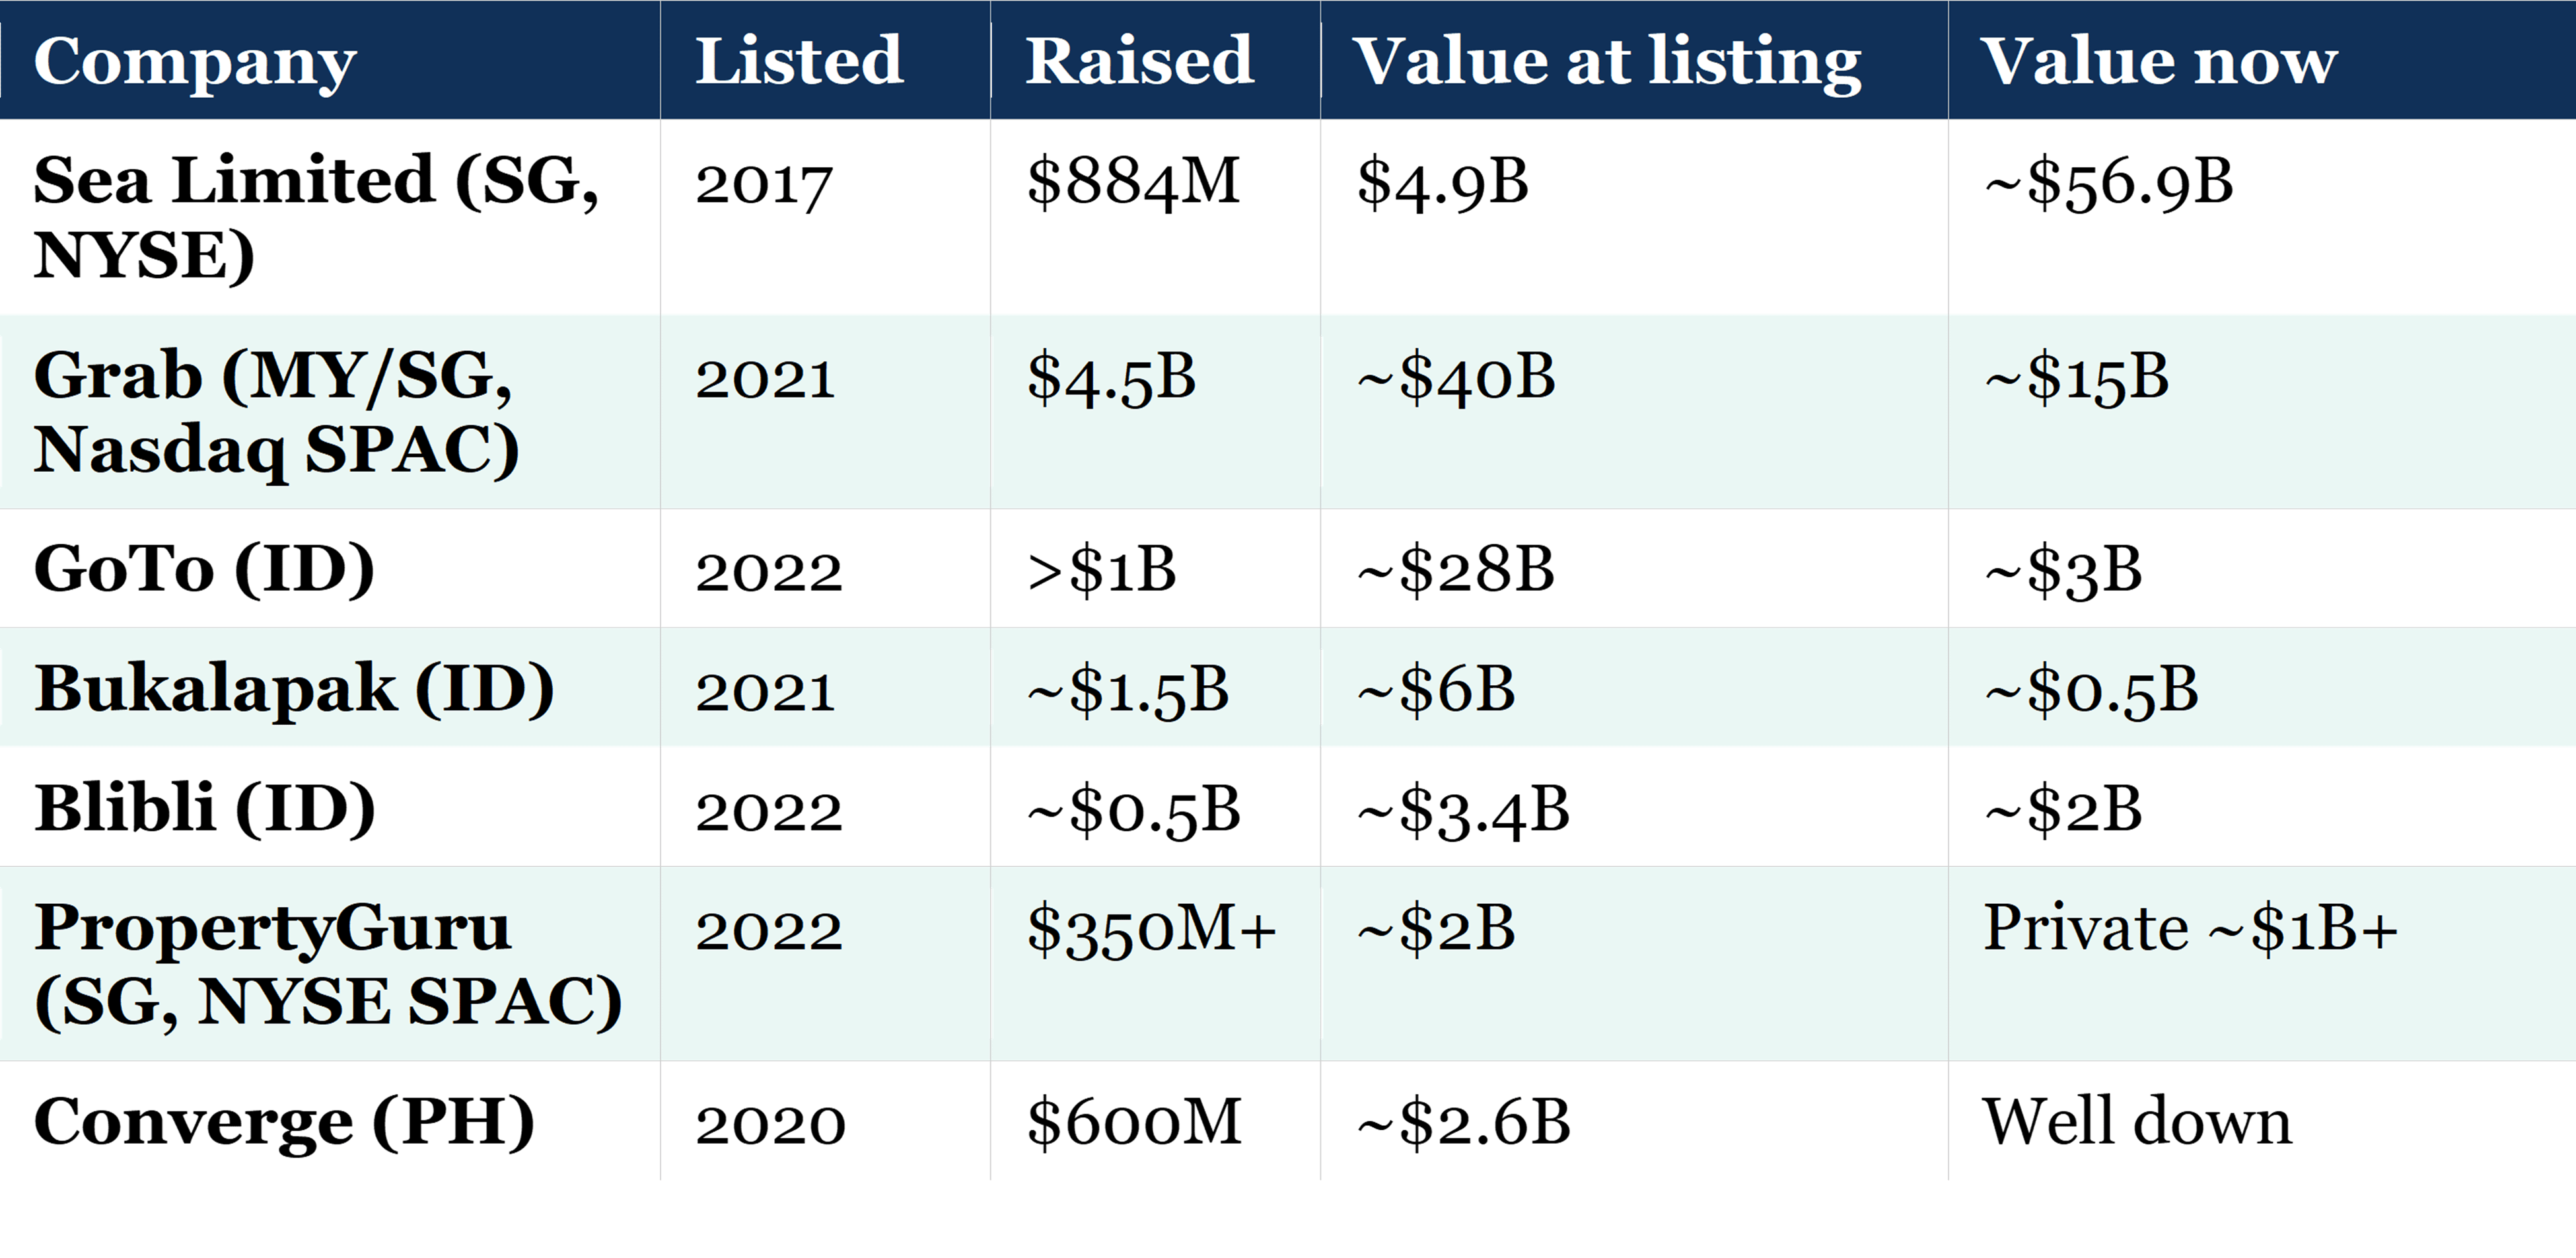
Since 2017, Southeast Asia has produced exactly one tech IPO that made public investors real money. One. And this week, the Philippines is getting ready to bet its entire year on the next one. So this week I want to talk about who is buying, who is selling, and which side of that trade you actually want to be standing on. Four stories, and they braid into one. We open with the good news, because there usually is some. Then we follow the money all the way to the part nobody puts on the deck. The smart money showed up twice in one week Start with the hopeful, because it is real and it is specific. This week two of the most serious institutions on the planet made their first proper bet on Southeast Asia. Not a press tour. Not a memorandum of understanding. Actual money into actual companies. The first: MIT, the university, joined the cap table of a Singapore company called PVX Partners. Not a flashy name, I had not heard of them before this. They do cohort-based financing for user acquisition. In plain terms, they fund the marketing spend for mobile games and consumer apps, and they get paid back out of the revenue those users generate. It came on the back of a ten-plus-million-dollar round with names like General Catalyst, and I think a DraftKings vehicle in there too. As far as I could find, this is MIT’s first major disclosed startup bet in the region. The second, and this one landed the day before I recorded: Pfizer Ventures, the drug giant’s venture arm, made its first Southeast Asian startup investment into a Singapore biotech called Engine Biosciences. Engine does AI-driven precision oncology, hunting cancer drugs with machine learning. They just opened a Silicon Valley office to go with the Singapore base. Here is why this is not just a funding roundup. When an elite American endowment and Big Pharma’s investment arm both pick Singapore companies for their opening move, in the same week, that is not a coincidence. That is a signal about where sophisticated capital now thinks the edge is. These are not tourists chasing a hot round. PVX is unglamorous infrastructure. Engine is deep science. Both are the kind of bet you make after you have done the work. Hold that thought, because the rest of this is about what happens to the money that was already here when it tries to leave. The Philippines is betting its whole year on one listing On the 27th, Mint, the company behind GCash, filed its registration with the Philippine SEC and its listing application with the stock exchange. The number: up to 92.3 billion pesos, roughly 1.5 billion US dollars at up to ten pesos a share, targeting a fourth-quarter debut. If it prices at the top, it is the largest IPO in Philippine history. Sit with the context. The Philippines’ IPO count for 2026 before this filing was zero. Nothing. So the country’s first listing of the year is also the biggest it has ever had. And it is a fintech, which if you have listened before you know is my home-turf bias made concrete. GCash put financial services into something like 90 million pockets. It is the rare regional company that is genuinely profitable. The pitch writes itself: the people who made GCash a habit can now own a piece of it. I want this to work. Let me say that plainly. Now the part that worries me, out loud, because that is the point of these episodes. The float is about 12%. Twelve percent of the shares go to the public market. The public is being sold a fairly thin slice while insiders keep the rest. And to fit GCash into its main index, the exchange is now considering cutting its own minimum public float rule from 20% down to as low as 12%. Take that in. The benchmark is bending its own rules to accommodate one company. When a market reshapes itself around a single listing, and that listing is carrying the whole nation’s IPO year on its back, that is not a recovery. That is concentration risk wearing a party hat. The real question: does GCash trade well enough to reopen the pipeline for everyone waiting behind it, or does one wobble set the Philippine market back another two years? To answer that honestly, you cannot just look at GCash. You have to look at what happened to the last batch of regional champions that rang the bell. Indonesia got a stay of execution, not a clean bill of health While Manila is opening a door, Jakarta is trying to keep one from closing. On the 24th and 25th of June, MSCI, the index provider whose decisions quietly move billions in passive money, deferred its decision on whether to downgrade Indonesia from emerging-market status to frontier. They kicked it to November. Indonesia keeps the badge, for now. Why was it even on the table? MSCI said, in effect, that it cannot trust the market. Lack of transparency in who actually owns the shares. Suspected coordinated trading that makes it hard to know what a fair price even is, or how much stock is genuinely free to trade. And the market rallied on the news. Here is where I get off the celebratory bus. That rally is celebrating a delay, not a fix. When the index provider tells you it cannot work out who owns the shares or what they are really worth, that is not a paperwork problem. That is a governance warning about the entire market. And look at the response. Indonesia is leaning on Danantara, the sovereign fund, plus insurance and pension money, to add buying support and prop up the exchange. Think about what that means. To pass a test about transparency and genuine free float, the answer is to bring in state and pension money to hold the market up. That is close to the opposite of the thing they are being asked to prove. A frontier downgrade is not abstract. It would force passive funds to sell Indonesian equities mechanically, which raises the cost of capital for every late-stage founder in the country dreaming about an IPO on that market, especially now without the hype cycle. November is closer than it sounds. Manila might be opening up, maybe. Jakarta is one review away from being pushed out. Hope on one side, risk on the other. So let me put some numbers on which way this bet usually goes. The receipts I promised you a number at the top. Here it is with the receipts. Since 2017, this is how Southeast Asia’s big tech IPOs have actually treated the public investors who bought in. SPAC valuations are listing marks, not day-one closes. Dollar figures are dragged by weak pesos and rupiah. Current values approximate. One winner. Sea Limited went out at a $4.9 billion valuation and trades somewhere in the $56 billion range today. Everything else is a shipwreck. Grab is down around 60% from its listing cap. GoTo lost roughly nine-tenths of its value. Bukalapak is trading below the cash it raised. Converge, the one Philippine name I could pull, is the cautionary tale sitting right next door to GCash. Now the caveats, out loud, because the show runs on honest data. The SPAC valuations were listing marks, not day-one closes, and several fell on the open. Currency matters too: weak pesos and rupiah drag the dollar figures down. On a per-share basis the returns are often worse than the market-cap numbers suggest, because of share issuances along the way. But the base rate for this region is brutal. If you bought the Southeast Asia tech IPO story over the last eight years, with one exception, you lost money. What actually breaks the curse Here is the thing that matters. Almost every one of those shipwrecks went public unprofitable, floated at the very top of the cheap-money window on a growth-at-all-costs story. GCash is not that. GCash actually makes money. That is the one real thing that could break the curse. The curse was never the business. The risk is the entry price. GCash is reportedly chasing a valuation around eight to nine billion dollars, against roughly five billion in the private market just a couple of years ago. That is the exact same “premium to the last round” framing that came right before every name on the shipwreck list. History says it is not company quality th… This is a public episode. If you would like to discuss this with other subscribers or get access to bonus episodes, visit seaofstartups.substack.com
Embed this episode
No transcript yet.