This message comes from KERA's THINK. THINK is a daily topic-driven interview and call-in program covering everything from history, current events, and technology to food and wine, travel, and entertainment. Subscribe to THINK wherever you get your podcasts. Planet Money is going on tour!
To celebrate the release of our first ever book, we are holding about a dozen events around the country. Details on cities and dates at planetmoneybook.com. That's planetmoneybook.com. This is Planet Money from NPR.
This seems like a pretty nice neighborhood. Yeah. Every house here, the lights are all out, so you're a little asleep. And we're sneaking up quietly in the car.
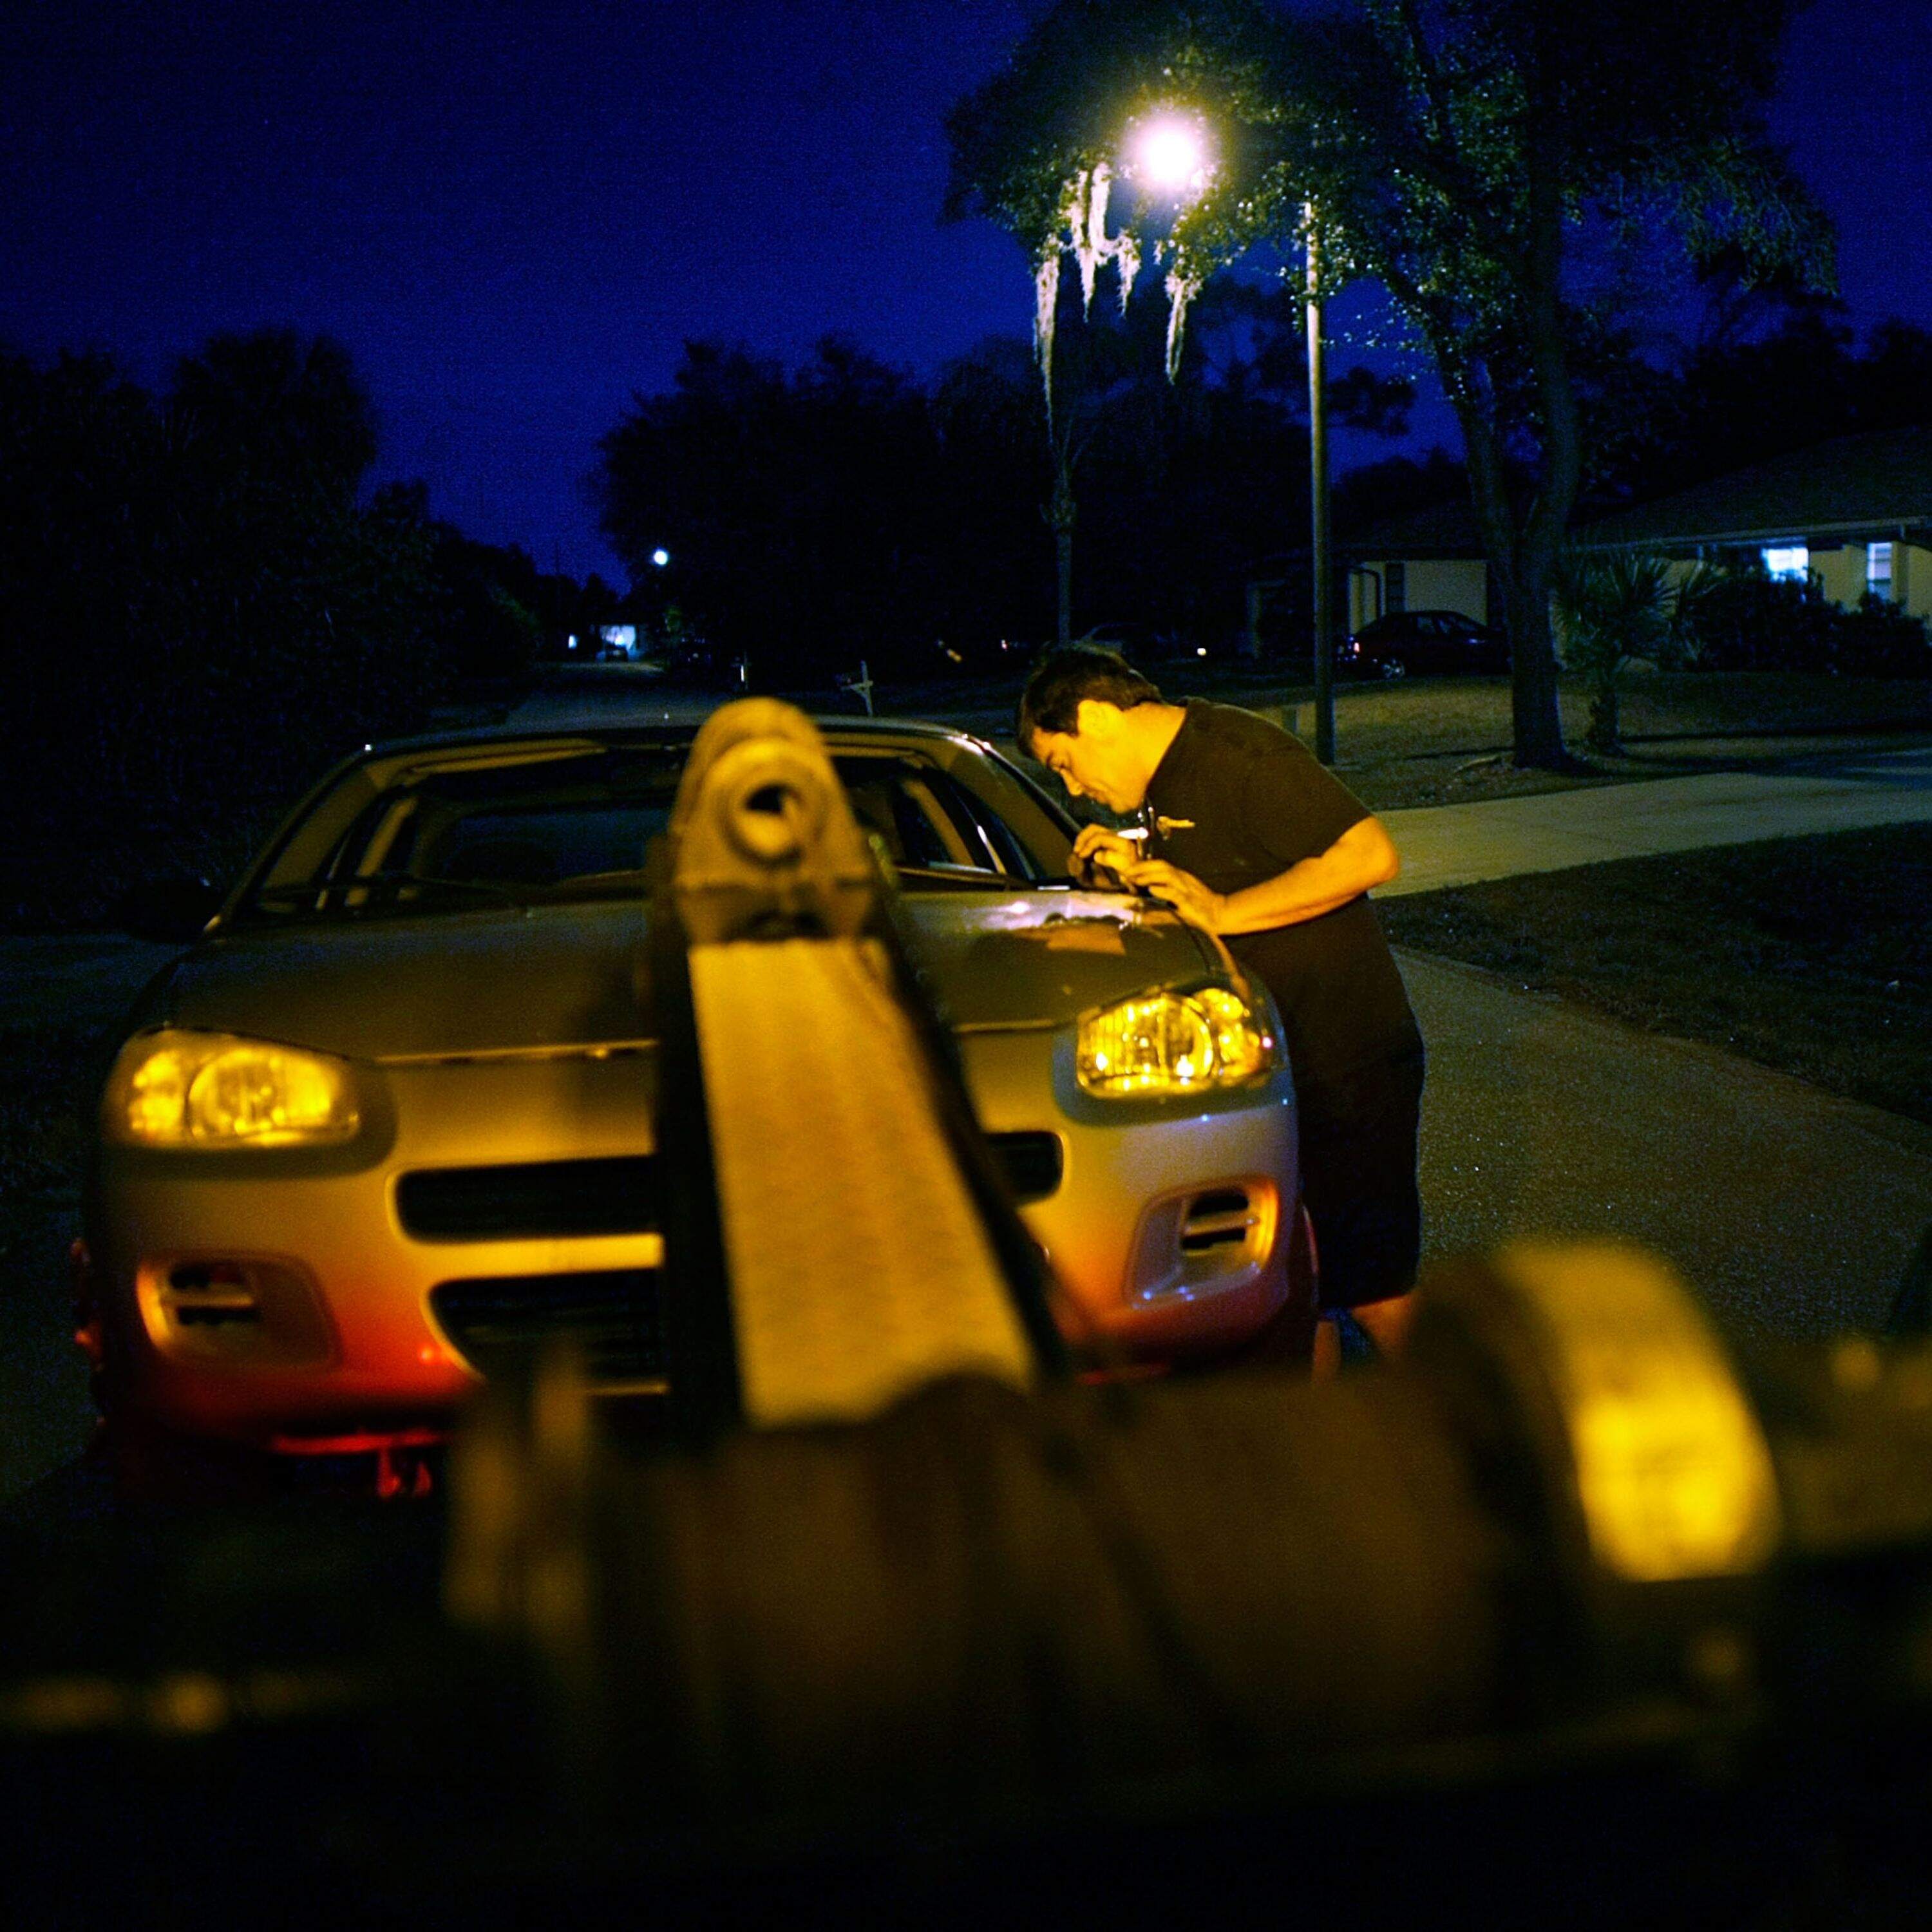
Larry Baker is a repo man. We're crammed in a surprisingly small tow truck, creeping through the suburbs in Ohio. Tonight, Larry's job is to find and repossess a black Chevy Cruze. The person who bought that car is about six payments behind, and the finance company wants its car back.
It's right there. What's that? It's right there. Okay.
Let me see. I thought I saw some lights on here. We pull up to a charming little house. It's a little garden, a couple of bird feeders in the yard.
The Chevy is sitting right in the driveway. The house is totally dark. What time is it? It's about one in the morning.
Yeah, I'm not going to knock on the door. Okay. Yeah, I'm just going to grab it. I'm going to drag it out.
Okay. My heart is genuinely pounding pretty hard. Like, there's a chance somebody is going to wake up and come out here. And if they do, then you deal with it.
We were out with Larry that night because we wanted to see on the ground what it looks like when a car gets repossessed when somebody stops making their car payments. And in this case, it's that black Chevy Cruze when Larry hooks it up to the back of his tow truck. Okay, so you're 100% sure this is the right car? Huh?
Yeah. Usually, Larry and his wife Maggie do these repossessions together as a team. She's out sick tonight, and it's left Larry a little exposed. He looks at the Chevy Cruze, then at the house.
Still no sign the guy who bought this car is waiting. So usually my wife stands by the door of the car in case he runs out, and that way she can stop him from jumping in the car. That certainly would be some exciting radio. We went on this ride-along with Larry a few years ago in 2019 because at that time, there was this really alarming trend in the United States.
About 7 million Americans were at least three months behind on their car payments. That's about the time that your lender starts thinking about repossessing your car. And today, we're revisiting all of this because in 2026, even more people are behind on their car payments. Even more cars are getting repossessed.
Hello, and welcome to Planet Money. I'm Kenny Malone. I'm Preeti Barathon. A repossession, it's kind of the end of a story.
One that's playing over and over again in this country with the same three characters. Today on the show, we're going to do something a little different. We're going to tell this story three different ways, Rashomon style, from three different characters' perspectives. The salesman.
If used car salesman is the worst person in the world, I am the king of the worst people in the world. The driver. I had the money. I had the means.
I was like, I'm getting a car today. And of course, the repo man. Four years of college, and I chose to do this. What'd you say?
And today, we're going to have an update from 2026. How dire the car loan market has become. Why more repossessions are happening. And is this a big warning sign for your car?
NPR's newest podcast is where you can find NPR's biggest interviews. I'm Steve Inske. The program is called Newsmakers. We talk to some of the most powerful and influential people at this moment to put real questions to them and push for real answers.
Follow Newsmakers on the NPR app or any podcast player, or you can watch on NPR's YouTube channel. Heads up, you're going to hear a lot of numbers in this upcoming session of the podcast. They're all accurate as of 2019, but we're going to update those at the end, so don't worry about that. Okay, so today, we are following the life cycle of a delinquent car loan.
We have three characters with three stories, and they're not directly related in real life, but they are all part of this same basic story that is happening over and over when a car is repossessed. So just know, not related stories, but we will be cutting in and out of them over the course of the next three chapters. Chapter one, the salesman. In our industry, PhD stands for Papa Has a Dealership.
Uh-huh, well, isn't that true for you? I technically do have a PhD there. Okay, I see, I got it. Rick Riker, like his father before him and his father before him, runs Riker Automotive, founded in the 1950s near Columbus, Ohio.
And as a third-generation car salesman, Rick talks in this great old-timey car lot jargon. PhD, for example, but also towers. That's where the sales director sit, thinking about credit scores and loan approvals. What kind of car a customer will actually be able to buy.
And while the salesmen are on the lot with customers, sales directors are running numbers up in their ivory towers. They don't sit above everyone else anymore and look down. Yeah, they did when I started. They looked down on the salespeople, they looked down on the customers.
Now we have everyone eye-to-eye. Their primary job is to know how to put that puzzle together. To some degree, our auto loan story starts here, with the towers. Because when you walk into a car dealership, there's a fundamental question the salesman needs to know.
Do you have good credit or do you have bad credit? And you never want to, as a salesperson, look at a guest and say, Hey, how's your credit? Do you think it's good or bad? Because if that person has good credit, they're offended, yes.
And they're saying, oh, wait a minute, are you implying that I might not have perfect credit? That's how good credit people talk, yes. Yes, that's how they talk. Actually, it's funny, I lifted my chin up and I kind of tightened my vest up.
If you have good credit, odds are you won't have trouble getting a loan with a low interest rate. You're in good shape. You can drive off with a great car. If you have bad credit, you're a riskier bet to lenders.
You're going to have to pay a higher interest rate for a loan, assuming someone is going to give you a loan. And Rick says there's this special move his salesman used just to float the idea that all people and all credit ratings are welcome at his dealership. We do what's called the Columbo, whereas you're walking on the lot to look at cars. You turn back over your shoulder and you say, and by the way, we have guaranteed credit approval if that's something you think you may need.
Why is that the Columbo? It's an old TV show, Columbo. That's what the sales trainers have called it for years. It's that kind of like look over the shoulder and give that squinty eye.
By the way, I noticed this. It's kind of a smooth way. They just call it the Columbo. The Columbo is a subtle way to let customers with bad credit know that Reichardt can still sell them a car and a car loan.
Reichardt also has a subprime financing company. And let's just talk about the term subprime loan for a second, because subprime does not mean bad loan. It just means loan to somebody who has bad credit. It is a riskier loan, and the interest rate will be higher.
And some people think that this practice on its face is predatory, that lenders can push people into cars they can't afford with incredibly bad loan terms. And Reich says part of the reason we are seeing more and more people fall behind on their car payments is that there are more and more questionable subprime model loans. A lot of lenders have gotten very loose. They have been extending credit and extending terms and extending money to individuals that probably shouldn't have had those terms of those loans and been able to buy those vehicles.
That, Reich says, is the irresponsible way to be a subprime lender. And you'll hear stories about this. Companies stuffing people into expensive, crappy used cars, wringing out as much money as they can, repossessing the car, even garnishing wages. Reich says there is a responsible way to be a subprime lender, and that is to think about the next car a customer with bad credit is going to buy.
If Reich hands that person a lousy loan for an unaffordable car, he's going to have to repossess that car and wreck that customer's credit, which is bad for future business with that customer. Oh my gosh, me as a dealer, I want them to make the payment. I want that car to get them where they need to go. I want their credit reestablished to where we can get them in a prime loan and really get someone back on their feet.
The subprime auto loan market is a critically important market when it is working well because people with bad credit and without a lot of money still need a car to live their life to go to work. And without subprime, they would not be able to get the money to get that car. And it's worth underscoring that the vast majority of people in this country with subprime loans are not defaulting on those loans. At least 92% of people who got subprime auto loans are paying them off on time, or at least they're not seriously behind on payments.
We asked Rick how many of the subprime loans his company issues result in repossession, and compared to other lenders, it is a loan number. I'm going to sound really nerdy because I think it's exactly 6% over the past two years consistently. So that is 6% of people giving a loan in a car and then it doesn't work out. That is very bad for that group of people, like not good for their life, it's bad for the credit.
Is there a way to avoid that, just get that number down to zero? Yeah, but one of the ways, so if we did that, that would mean that we're basically declining and just telling people we aren't going to give them a loan. So as long as we want to play in that field of lending, there's always going to be some form of repossessions. There's just no way around it.
But also Rick says, there's no surefire way to predict who is going to default and who isn't. Credit scores don't tell you if somebody is going to be in the hospital in a year or lose their job. There's just no perfect way to predict what's going to happen in somebody's life when they walk into a car dealership. Can I ask a question before you go to the dealership?
Okay. Chapter 2, the driver. So what car do you have in that moment? I believe it was a 2007 Ford Explorer.
Okay. A nice car. Yeah, it had almost like 400,000 miles on it. Yeah, that's a...
Driving a Ford Explorer that's shaking a little bit, you kind of want to get something different. Oh, was it shaking a bit? Oh, yeah. I hit that 70 miles per hour mark on these highways.
It gets a little sketchy. Stephanie Waldrop lives in a small town in Mississippi. She's 23 now, and a year ago, she was working at a fast food fried chicken restaurant. She'd been there for a while, started as a cashier, moved up to shift leader, then to manager.
So you got this new job, and I imagine it came with more pay. Yes, honey, it did. So you were making pretty good money. It was great money.
Look, it was money that I didn't understand what to do with it. Stephanie was making four grand a month, and she kind of did understand what to do with it. Upgrade her crappy Ford Explorer. Did you have a dream car in mind?
Well, you know, I'm a very... Not really simple. I'm complex, but simple at the same time, you know. I'm very much an SUV person.
Okay. So I wanted a Ford Flex. We had to look up the Ford Flex, and it is an unusual-looking car to pick as a dream car. To me, it looks like a horse, and I think it's kind of cool.
So therefore, I wanted that. Like, I'm kind of gothic, you know, but I'm actually quite bubbly sometimes, so... Bubbly gothic is the best way to describe it? Yeah, yeah, I'm a bubbly goth.
So just before her birthday, Stephanie drives her shaky Explorer to a dealership in Mississippi. Stilton there says, But the good news? This dealer could still get her a subprime loan for a different car. I used Ford Fusion.
You know, it was red. Like, that's my favorite color. Being colorblind, that's the one color I can see very well. So that's why I wanted that red car.
I was like, it is red, so let's go for it. Now, let's just talk about the terms of subprime auto loans for a second, because Stephanie was not going to get a favorable loan, to say the least. This was about a $12,000 used car. Her interest rate on the loan was going to be 23%.
So with fees and taxes, her payment was going to be $466 per month for 48 months, and she was going to end up paying almost double the sticker price of the car. Some people say this is why subprime is predatory, but others say this is kind of the deal. This is why it costs to cover a higher risk of default when someone has bad credit. But these are the kinds of terms on subprime auto loans.
Interest rates in the high teens, low 20s, and sometimes they'll be stretched out for seven or even eight years. So Stephanie's looking at a car that's not her dream car, and thinking, it's better than the shaky Ford Explorer. She's looking at a loan that is definitely not her dream loan, and thinking, I mean, I can't afford it. $466 a month?
I make $4,000 a month? Okay, let's do this. And over the next year, she made her payments, she kept working at that fast food restaurant, making great money, but she says there were things at that job that just started to take a toll on her. I am a transgendered woman, so there's a lot of discrimination that comes along with that.
It just kept happening more and more frequently. I had a couple workers there that would call me it, and then the guests, the customers and stuff that would come into the store, it was something else. I mean, they would sit there and just ask, what are you? Blankly just ask that.
And so it started weighing on me. For a while, I don't really care. But in the back of my mind, it really weighed on me really hard. Eventually, she says it was just too much.
She found a new job that was better for her, and she quit the restaurant. The problem was that this new job, it paid a third of her old salary. She knew there were going to be huge trade-offs, including that expensive auto loan. When it comes to your mental health and something that's material, the mental health outweighs material any day.
So Stephanie missed her first payment, and the finance company starts calling. They're calling asking what I'm going to pay, and they'll just sit there and pressure me, and like, well, we need you to pay something now. I'm like, well, when the manna from heaven falls, then I'll pay you. It's like, it's kind of hard right now.
After three months, Stephanie was about two and a half payments behind, and that is when her lender decided they wanted a car back. It was a morning, a weekday. She had the day off from her new job, and she was in her kitchen. I'm there at the dishwasher bringing dishes in there, and cleaning up afterwards, and our window points straight towards the driveway.
And I see this white tow truck hooked up to my beautiful red car. Oh, no. And I'm like, uh, I have a situation. Like, I was freaking out.
I was like, no, no, no, I'm not that far behind. Why are you taking my car? But I mean, it must cross your mind that you're like, this is what happened, I guess, when I skipped those days. Yes, it's like, this is what happened when I laid this down in order to pick up another part of my life.
So you're 100% sure this is the right car? Huh? Chapter 3, The Repo Man. When we met Larry Baker, it was about 9.30 at night.
He was waiting for us in his tow truck, which was parked in front of his boat, which is named Final Notice. And the Final Notice on the boat means if I come, I'm your Final Notice. Ready to load up? Yeah.
Larry's wearing an Ohio State crewneck sweatshirt. He's got a small hoop earring. He smokes palm cigarettes, but he's trying to quit. And at least tonight, his radio is tuned to the classic rock station in Columbus.
You want to get some? Yeah. Thanks. We rode along with Larry from 9.30 p.m.
to around 1.30 in the morning. This time I'm not always get coffee. You guys drink coffee or no? Oh, yeah.
Okay, Speedway coffee's the best. Wait, really? Oh, my God, yes. Speedway coffee.
That is repo lesson number one. Here is what else you'll learn over the course of four hours with a veteran repo guy. Lesson two, do your repossessions in the middle of the night, because if people are sleeping, there will be less conflict, but that doesn't mean zero conflict. Yeah, I didn't bring it tonight.
That's why I carry 45 out of the bag. How many times have you had to pull a gun? Twice. In 15 years.
And you've had a gun pulled on you? About four times. Okay. But lesson number three, most people are good.
And remember, you are meeting them at one of the worst moments in their lives. You know, when they treat me with respect, you know, I have a heart too. So there's been times where I've left cars. You know, finance company wanted me to get a car, and, you know, I looked at paperwork.
They only owed $300 and some dollars, and I thought, you know what, this car, it really is a piece of junk car. The four girls paid for it for, you know, two years. I just left the car. I told her to go hide.
The repossession business has changed dramatically over the course of Larry's career. He's been doing this for more than a decade, and here's how he says it worked when he started. A lending company would get in touch and say, hey, Larry, so-and-so stopped paying. We need her car back.
So in those olden days, Larry wouldn't get much more information than that. A name, an address, a phone number. But maybe so-and-so moved. Maybe she isn't picking up her phone.
Now what? Larry then had to become a kind of detective. He would go on the social media of the day, MySpace, and he would see if so-and-so was posting pictures of herself. What's in the background of the picture?
Does Larry recognize it? Can he drive there? Maybe the car's there. He also checked databases to find other addresses, other phone numbers.
And if that didn't work, he'd try to find so-and-so's family members and just start making phone calls. You have to do a little trickery. And, you know, I might call a cousin and say, hey, this is John from Rent-A-Center. Your cousin, so-and-so, came in to get a, you know, widescreen TV.
We want to get it delivered to her, but we need to verify three pieces of information. So now, I got our new address. Are you allowed to do that? Yeah.
So you can imagine, lenders were a little more reluctant to give out subprime loans back then. But things have changed. It's got to... way easier to get a car back.
All right, so what's next? Okay, I'll show you. Larry pulls out this iPad to show us the next car on his repossession list. It's a black Chevy Cruze.
The car was bought with a subprime loan. The buyer has stopped paying, but here's the catch. Nowadays, Larry says, part of the deal when you buy a car with a subprime loan is that the lender is going to stick a GPS tracking device onto your car. So now, Larry doesn't need to go on MySpace or fake a phone call.
He just opens up an app on his iPad and punches in this car's GPS number. GPS don't lie. Okay, so we'll ping it. Oh, you're like, we pull up the live GPS here?
Yep. Up on the map, which is a little dot in a pretty nice neighborhood. This is where the car is. Yep, that's where it's at.
What if it's in the garage? It's not. This thing paying is pretty much accurate. It does seem like your job is much easier now.
Larry says finance companies now know that if they issue a risky loan, it's going to be much easier to get their car back if someone stops paying. And that is definitely a part of the reason we are seeing more subprime auto loans. When you know you can get the car back, it is that much less risky to issue the loan. And it is amazingly easy to find a car this way.
It's right there. This is, in fact, the car we were repossessing at the very beginning of the episode. Larry is running around the driveway, hooking this Chevy Cruze up to his tow truck. All right, so it's like one in the morning.
Larry trails off. He's focused on his actual job, which is getting into his truck. Pressing a button that pulls the Chevy into the tow position. Nobody wakes up.
Nobody runs into the car. Larry hits the gas. He drives away. See, adios.
That's it? See, all the time. Is this what a normal rego looks like for you, Larry? Yep.
Five minutes. Five minutes. It would genuinely be miserable to wake up and not have your car the next morning. I personally have to go to work, right?
Oh, yeah, I mean, it is. I mean, I feel for some people. I really do. You know, taking somebody's property and, you know, make them, you know, stranded.
You know, they could have, you know, a couple kids and really went through some hard times. I mean, we've even taken a car and gave them money, you know, because they didn't have any money to get a catch a bus. They had to go to work or catch an Uber. You know, we all have fair bills.
This is how I pay my bills. This is how I feed my family. So it's just a job. Millions and millions of Americans are on the verge of having their car repossessed.
Some people are calling this a subprime auto crisis. But look, this is a different kind of crisis than the subprime mortgage crisis of 2007. There are a lot of reasons why, but probably the simplest is that there's just way less auto debt. The mortgage market was and still is much, much bigger than the auto loan market.
That said, an auto repossession is clearly a crisis when it is your car being taken. After the break, what really happens after a repossession? Since the Supreme Court weakened the Voting Rights Act of 1965, Southern states are redistricting. Tennessee was the first state to make it happen.
The Republican supermajority there broke up the state's only black majority district. Two years ago, we embedded with the Tennessee legislature to understand what one-party power looks like. Listen to Supermajority for NPR's Embedded, Season 19. Yes, yes, it is.
When the day came for her car to be repossessed, Stephanie Waldrop says she actually recognized the repo guy. He used to come into a chicken restaurant when she worked there. He was a nice guy, she says, even gave her time to clean out her car, grab her beloved umbrella. It's wonderful.
It's huge. It's just black. It's just massive. Like a funeral umbrella.
It's your gothic side. Yes, it's a gothic side coming out. One of Stephanie's goals with that car was to build her credit back up, but the repo has not been good for her credit score. It dropped like a bad habit, honey.
How did you feel when you saw your credit score? I was a little upset. I was put back a little bit, but it's like, I'm going to fix this. And technically, she still does have time to fix this.
Here's the situation. Stephanie's car has not yet been auctioned off, and until that happens, she can get the car back. She'll need to start making regular payments again, plus a new $700 repossession fee. So her plan is to find a second job to get the money she'll need to get her car back.
Of course. All of that will be harder because she doesn't have a car anymore. How are you getting around now? Ah, honey, sometimes I don't even know.
Yeah, how are you getting home? Oh, my boyfriend's mom. She's going to take me to work. After this, I'm going to work.
Oh, okay. Well, good luck on the car. Update us if you get the car back. Okay.
Okay, so that is where we left things in 2019. And since then, there have been a lot of things that are worth updating. So let's start with just the repo business in general. It's been very busy.
Now, there was a brief lull in collections during the pandemic, but otherwise, repossessions have been rising steadily. And when we went to talk to Larry Baker, the repo man that we followed, he told us that Larry told us that his brother-in-law was shot in the leg trying to repossess a car. Before, they just didn't care. Come get it.
I don't care. Can't pay for it. Now, I want to keep it no matter what. So desperation is the biggest change that Larry says he has seen.
Now, there are whole companies that track numbers of repossessions in the economy, and they are still working on the final tally for 2025, but they estimate it will end up as more than 3 million cars repoed last year, and that would be more than 2019. And it would also be on par with how bad it got during the Great Recession. Now, meanwhile, Larry Baker himself, his biggest update is that he is now out of the repo business. It was a good run.
We've been doing it since 2006. We made a good lick of money. Time to say goodnight. Larry retired in April.
Now, on to an update of the second side of our car loan, the dealer. Rick Reichert left his business as well. His old dealership is now in the hands of a different Reichert. The process hasn't changed.
I think the tools in which we use to get there has changed a little bit. His cousin Jared told us that the Colombo method of selling a car, that left with cousin Rick. Yeah, the Colombo method is Rick Reichert. Rick's a way better salesperson than I am.
Jared told us that repos on his lot are close to double what they were in 2019, and he says a big reason for that is that cars now are simply more expensive. Because, you know, in 2019, you could find a $10,000 to $15,000 car for a subprime loan. Now, I mean, you're looking $20,000, $25,000 vehicles. So that's why we're reaching the bank saying, hey, can we stretch this loan?
You usually do it 60 months. Can we do it 84 months? Now, the downside to a longer car loan is that the car owners will end up paying more in interest than overall, which means a higher chance borrowers might not be able to pay for it, which means more risk for everybody. And remember, this whole trend is mostly about subprime borrowers, people with bad or even just okay credit scores.
And last fall, 6.6% of subprime borrowers had fallen at least two months behind on their auto payments. That may sound small, but that is the highest it's been since, like, even before the financial crisis. Now, all of this is part of what feels like an affordability crisis for so many Americans, as we've reported on a few times already, which I suppose brings us to our final update, our car buyer, Stephanie Waldrop. Now, shortly after we aired the original episode, people started reaching out asking how they could help Stephanie.
The donations poured in. She was able to go back and buy her specific car back. I drove it all the way back home. It took about 20 minutes to drive.
Oh, it felt so great. It felt so great when I got behind the wheel of my car. We were not able to track Stephanie down again in 2026. So, Stephanie, may you still be driving the car you love with a check engine light that never comes on in a full tank of gas.
Give us an email if you hear this. We'd love to know how you're doing. If you like stories like the one you just heard, and if you also like reading stories, well, Planet Money has a book coming out in April. And look, you can find a link to order the Planet Money book, including from your local bookstore at planetmoneybook.com.
It's a great gift. This episode was originally produced by Darian Woods and edited by Brian Erstad. Our update was reported by Vito Emanuel, produced by Sam Yellowwarskessler, engineered by Sina Lofredo, and it was edited by our executive producer, Alex Goldmar. And you know what?
We may as well give you an update on my co-reporter for this episode, Briefly Fairathon. She now is a big wig making podcasts for ESPN at 30 for 30 and was a finalist for a whole surprise as well. We're very proud of you, Briefly. I'm Kenny Malone.
Every White House has an official counterterrorism plan, a strategy document basically, but President Trump's new 2026 plan shifts focus to left-wing extremism. We're unpacking what's in the document and who influenced it this week on Sources and Methods. You can listen on the NPR app or wherever you get your podcasts.