Valuing an American Option Using Binomial Tree-Derivative Pricing in Excel
from Harbourfront Technologies Hosted by Harbourfront Technologies
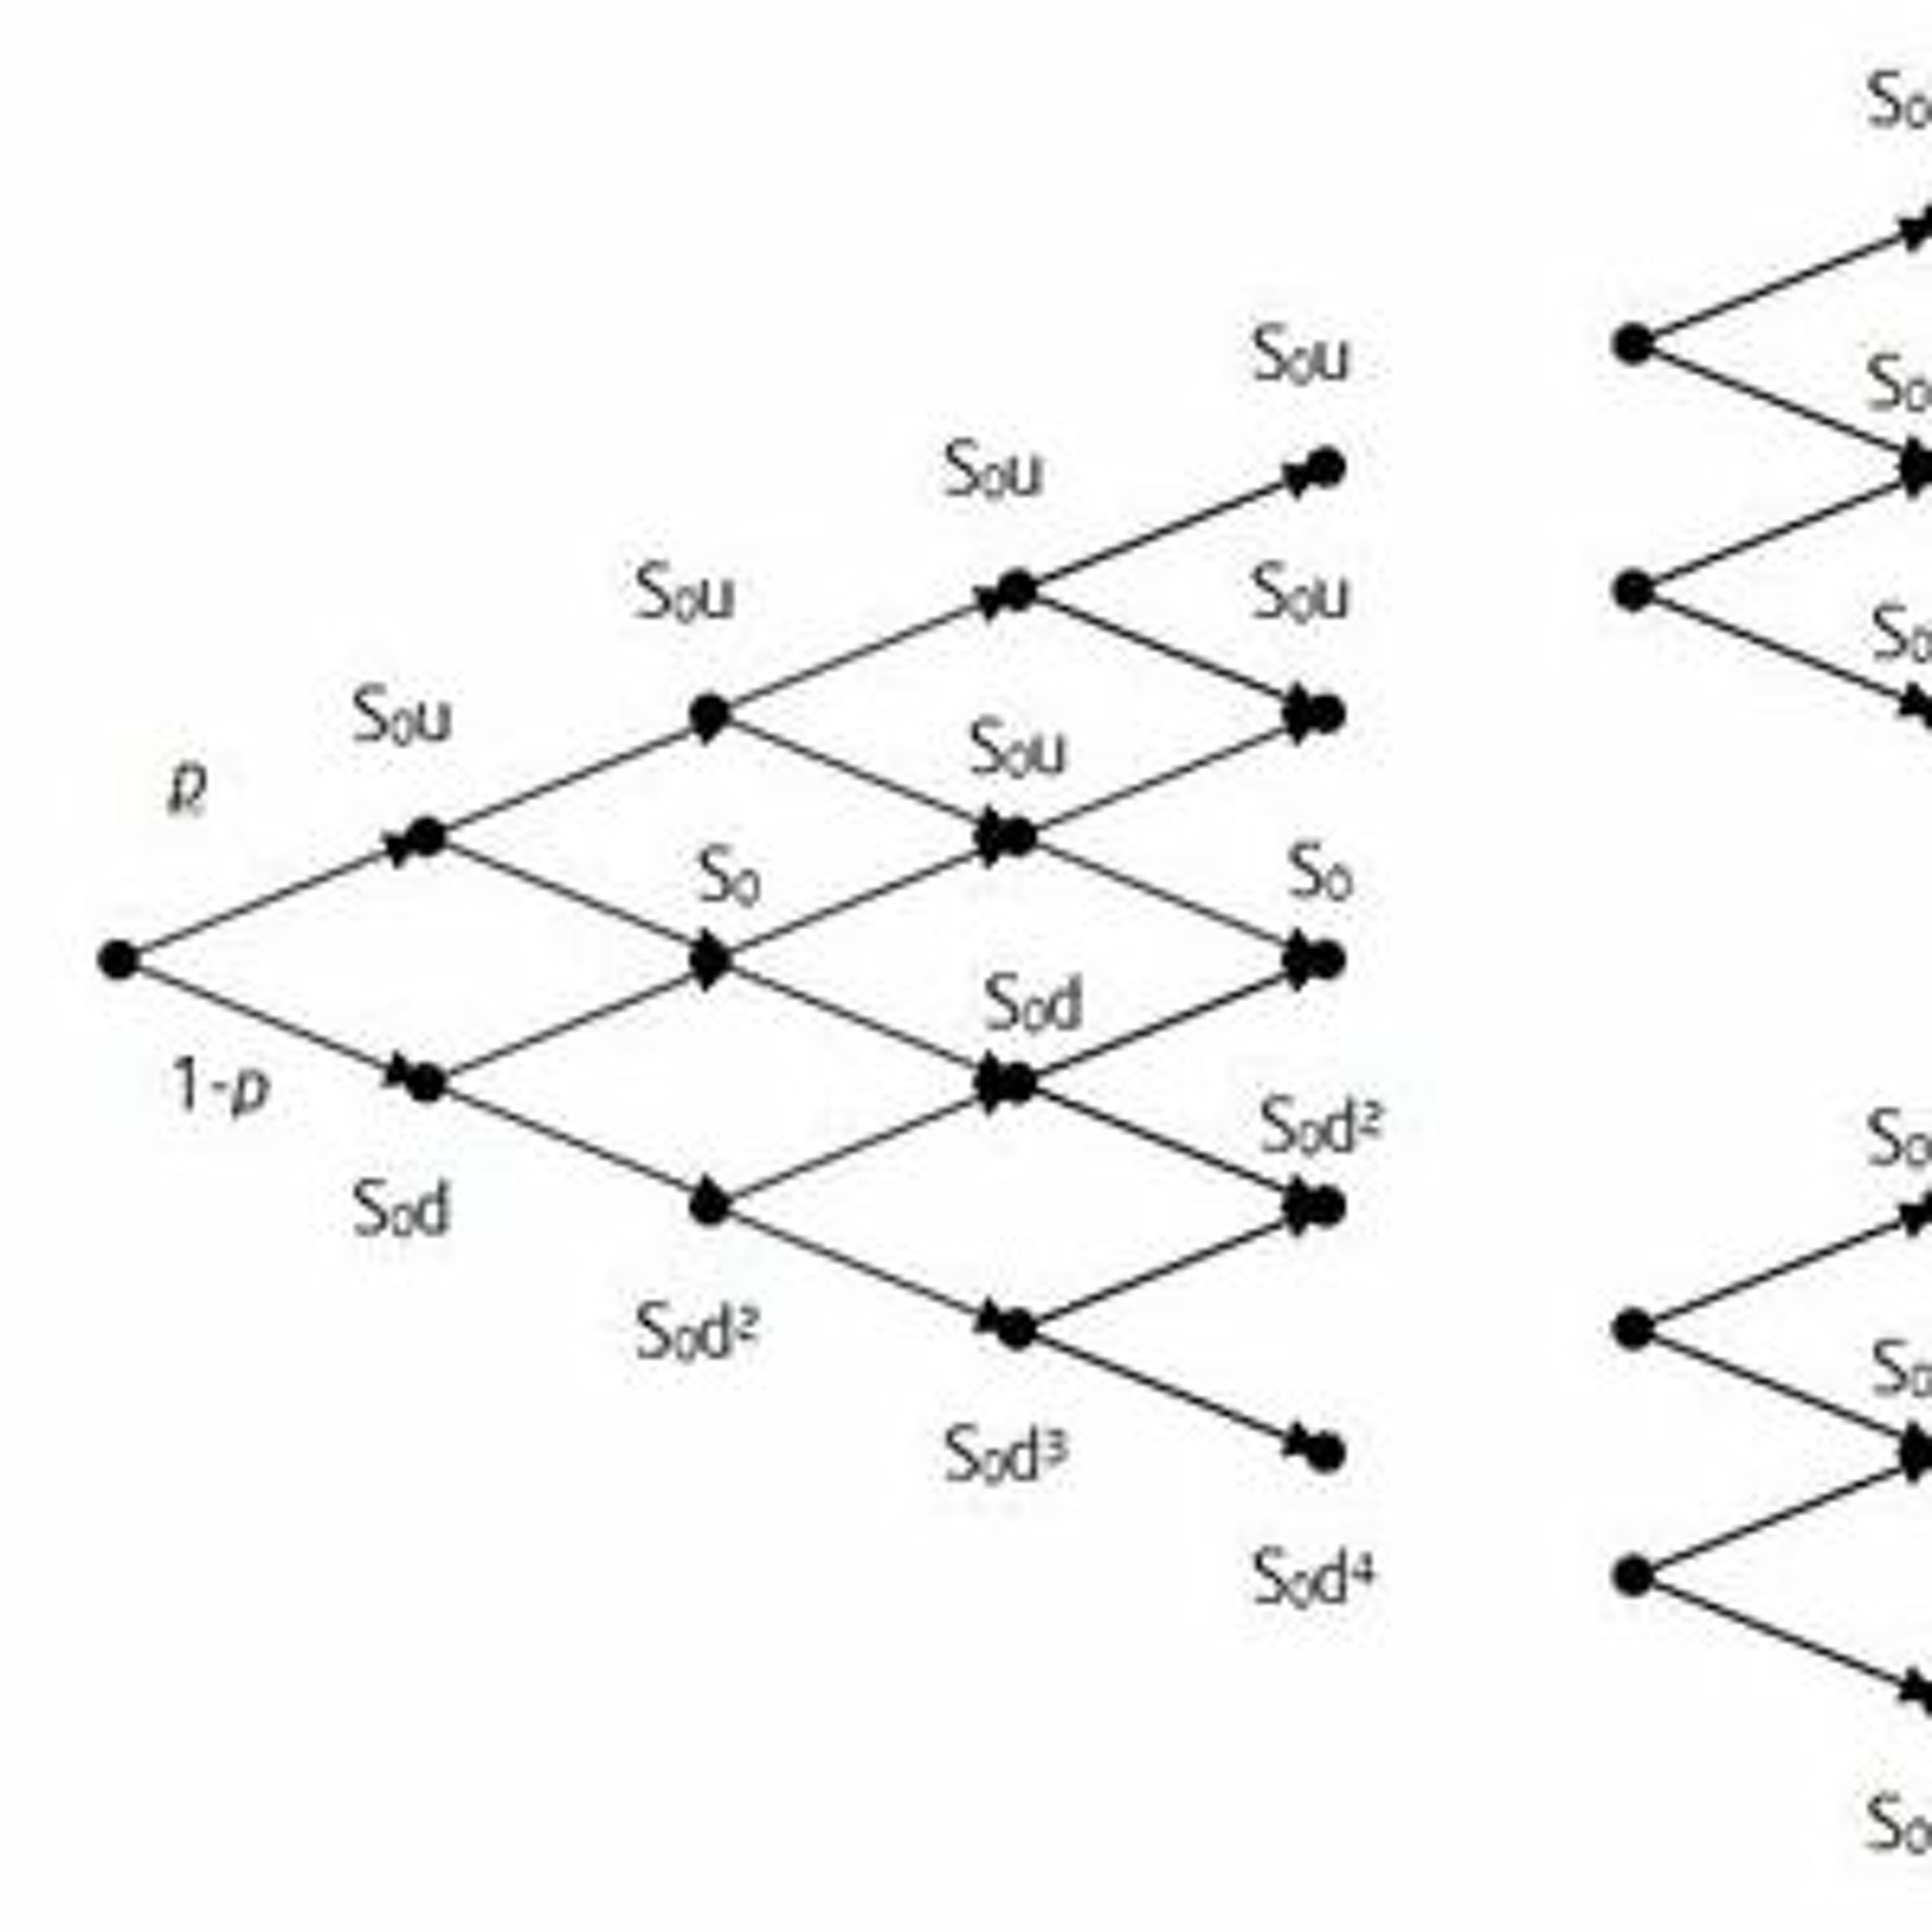
We’re going to use the binomial pricing model to value an American equity option. Essentially, the model uses a “discrete-time” model of the varying price over time of the underlying financial instrument. Valuation is performed iteratively, starting at each of the final nodes, and then working backwards through the tree towards the first node. http://tech.harbourfronts.com/derivatives/valuing-american-option-using-binomial-tree-derivative-pricing-excel/
Embed this episode
No transcript yet.
Similar podcasts
Build Amazing Things (securely)
Laura Bell Main
Featuring guests from around the world and builders of some of the most exciting technologies on earth, join us as we explore the world of innovation and technology and what we need to do as engineers to keep it safe and secure.
HCI Growth Catalyst
HCI Podcast Network
Welcome to ”HCI Growth Catalyst,” the podcast dedicated to exploring the transformative power of Learning and Development (L&D) within organizations. In each episode, we dive deep into the world of L&D, uncovering innovative strategies, best practices, and real-life success stories that propel businesses forward. From cultivating a culture of continuous learning to leveraging cutting-edge technologies, we leave no stone unturned when it comes to fostering growth and development. Join me as we engage in thought-provoking conversations with industry experts, renowned thought leaders, and seasoned practitioners who have witnessed firsthand the profound impact of L&D on organizational success. We explore topics such as leadership development, employee training, talent management, and organizational change, offering practical insights and actionable strategies that you can implement immediately. Whether you’re an HR professional, a learning enthusiast, or a business leader passionate abo
Workforce Insights with Employ Milwaukee
Employ Milwaukee
Milwaukee’s workforce development ecosystem constantly adapts to change as it responds to economic disruptions, new technologies, socioeconomic disparities, and now the impact of a global pandemic. Over the next decade, change will be even more dramatic, opening a whole new spectrum of possibilities around the notion of work and what both workers and employers need to be successful. Join workforce leaders from the public and private sectors, as they discuss insights, trends, challenges, and solutions. If you want to learn more about the opportunities we can embrace to ensure equity, expand job readiness, and catalyze collaboration among stakeholders, this podcast is for you!Hosted by Ausha. See ausha.co/privacy-policy for more information.
Frequently asked questions
How long is this episode of Harbourfront Technologies?
This episode is 2 minutes long.
When was this Harbourfront Technologies episode published?
This episode was published on April 6, 2019.
Can I download this Harbourfront Technologies episode?
Yes. Use the download control on the episode player to save the publisher-provided media file.