
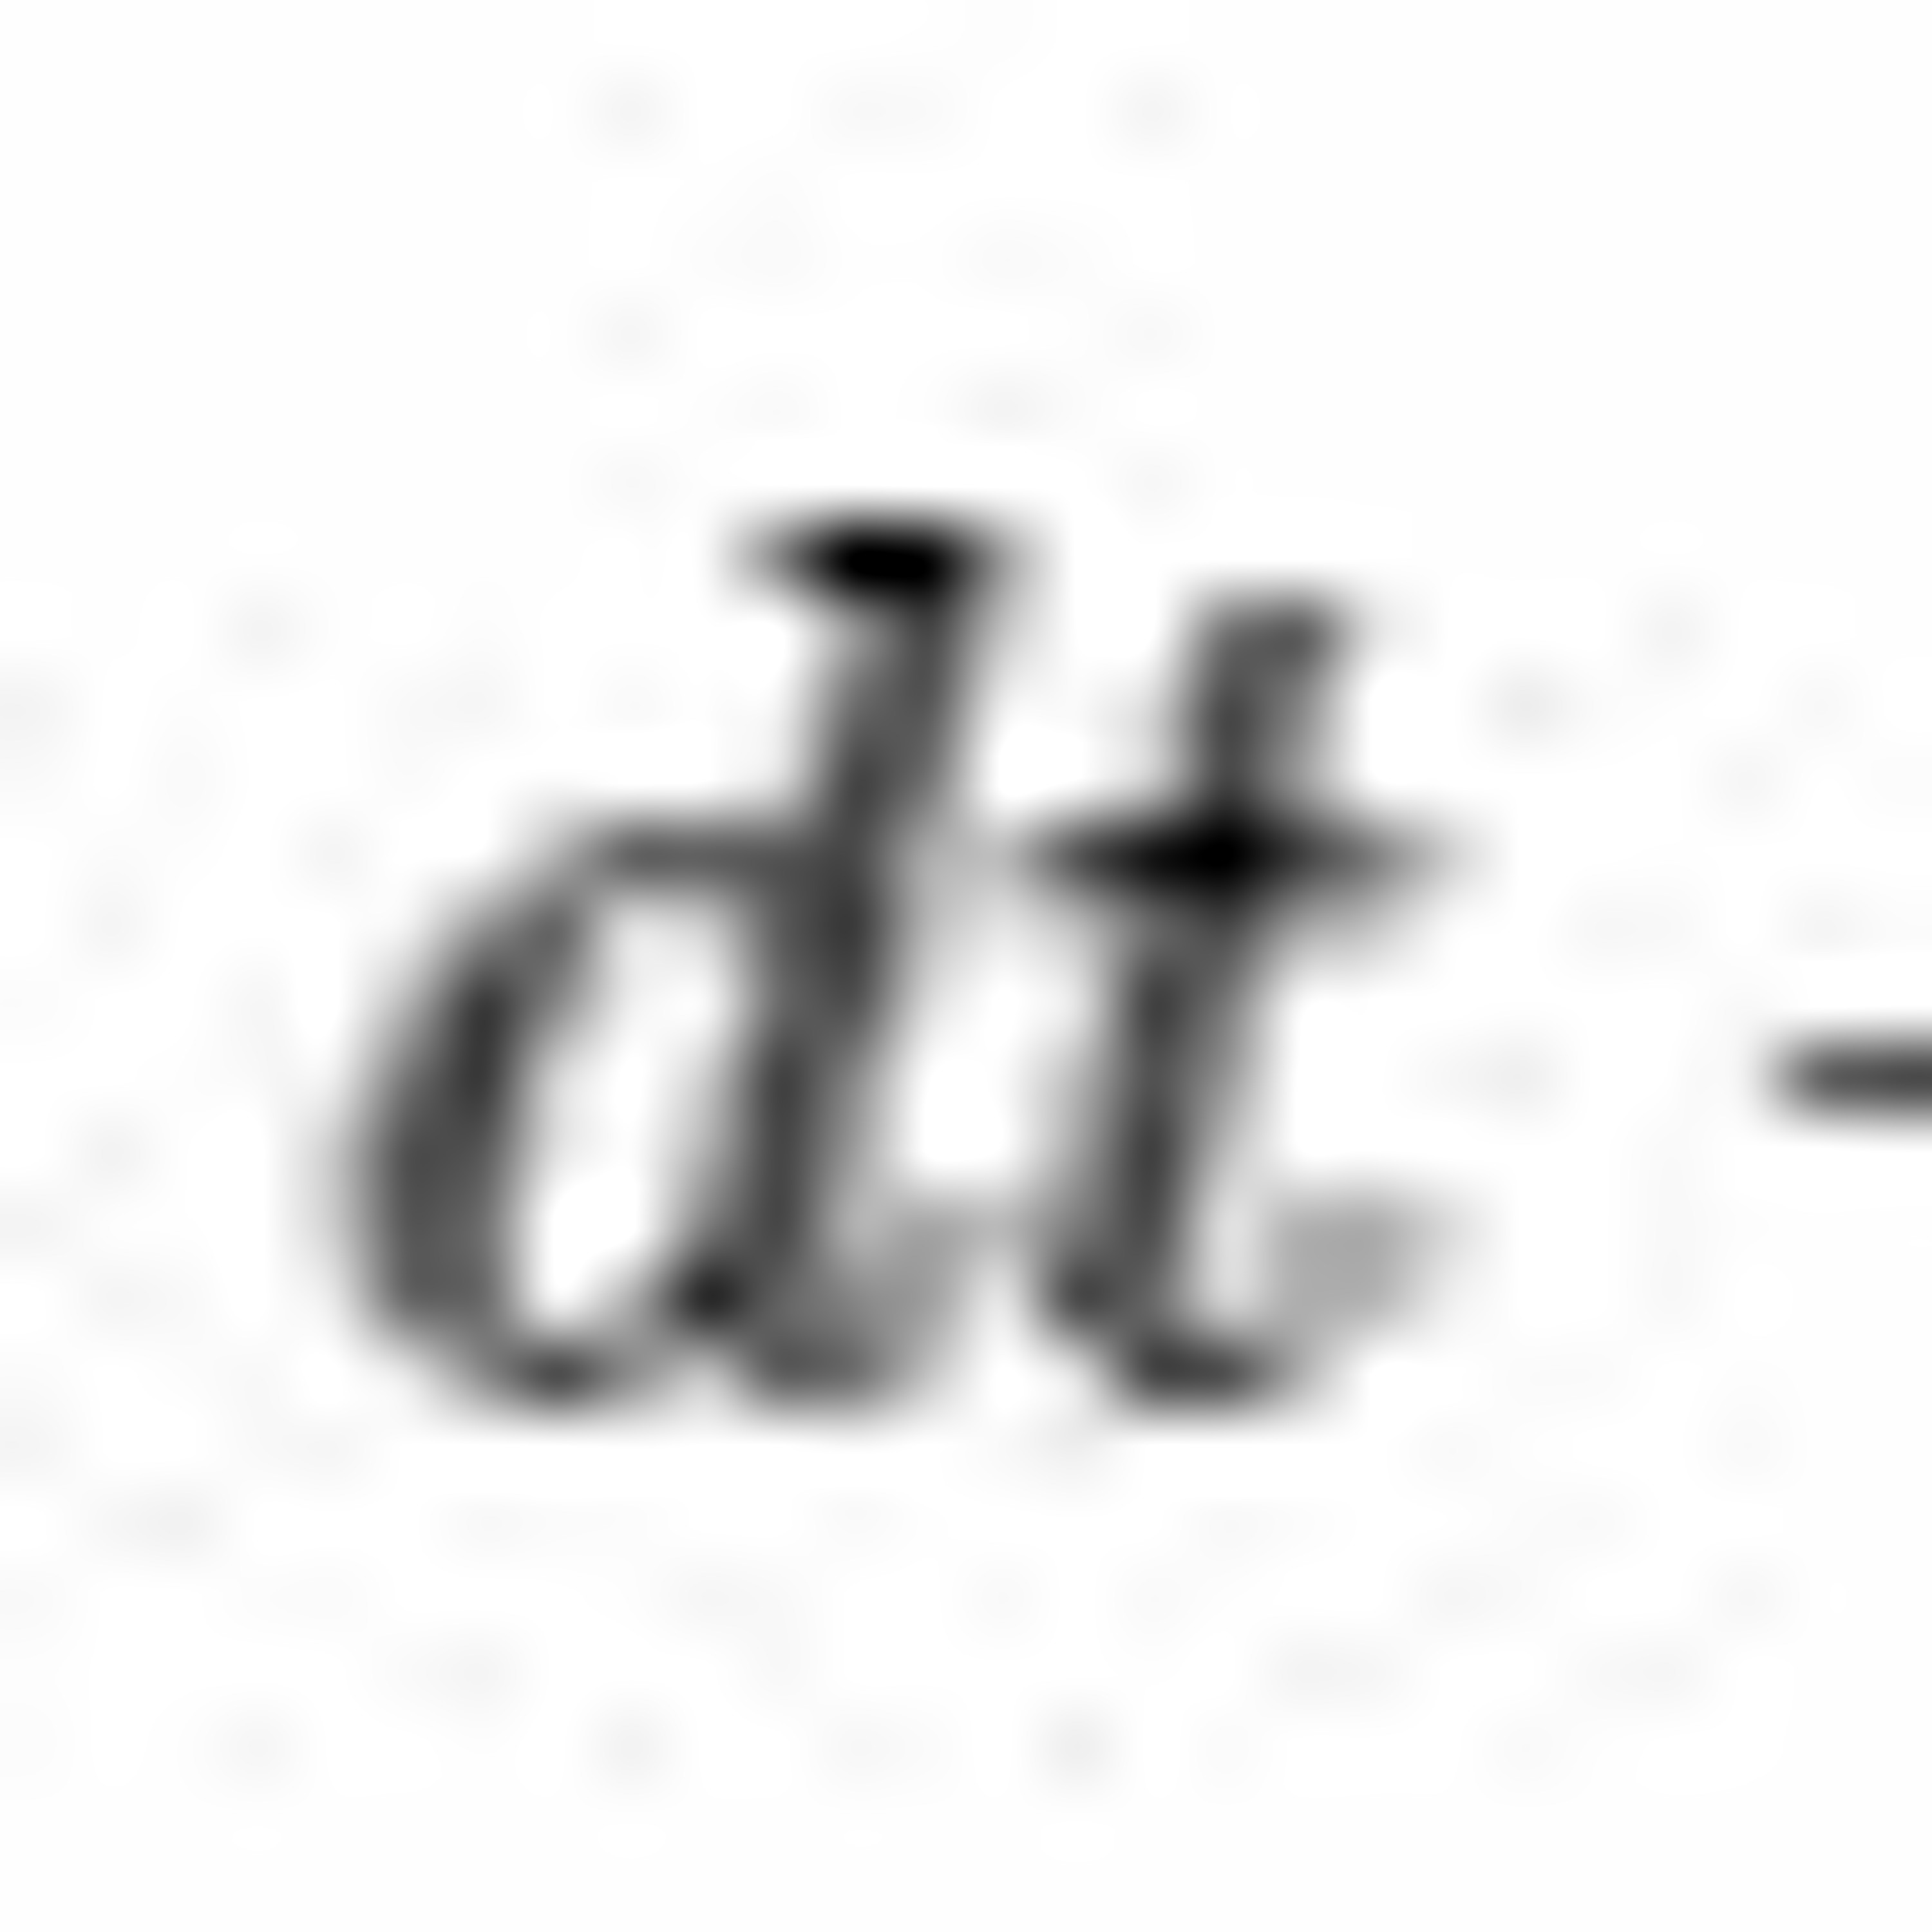
EPISODE · Feb 7, 2020 · 2 MIN
Valuing European Options Using Monte Carlo Simulation- Derivative Pricing in Python
from Harbourfront Technologies · host Harbourfront Technologies
To price the options, we first simulate the price paths using the following Stochastic Differential Equation. The simulation is carried out until the options’ maturity. We then apply the terminal payoff functions and calculate the mean values of all the payoffs. Finally, we discount the mean values to the present and thus obtain the option values. http://tech.harbourfronts.com/derivatives/valuing-european-options-using-monte-carlo-simulation-derivative-pricing-python/
Embed this episode
Ready to play
Valuing European Options Using Monte Carlo Simulation- Derivative Pricing in Python
No transcript for this episode yet
Similar Episodes
No similar episodes found.